Category

Insurance

Category

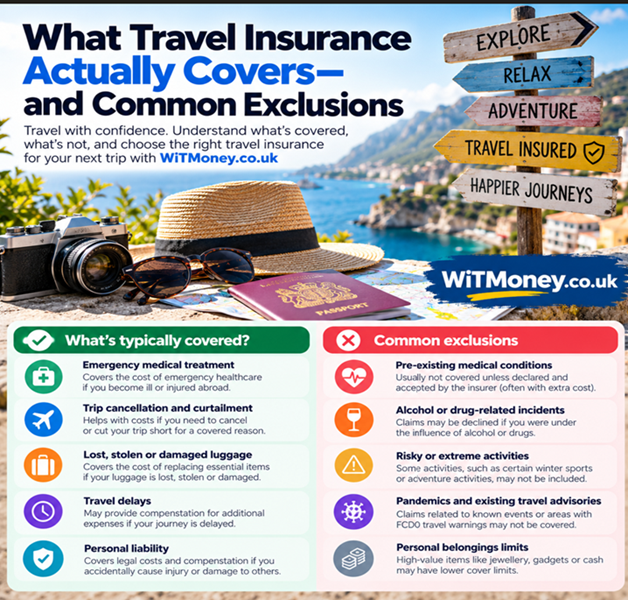
Travel insurance is designed to protect you financially when a trip goes wrong, but not every policy offers the same level of cover.

Some policies focus heavily on medical emergencies. Others provide stronger protection for cancellation, baggage, delays or missed departures. The important thing is to understand both what is covered and what is excluded before you buy.

Travellers comparing policies can use WiT Money’s travel insurance comparison to review different types of cover and the features available.

What Does Travel Insurance Usually Cover?

Most travel insurance policies include a combination of the following areas:

  • emergency medical treatment
  • cancellation and curtailment
  • lost or stolen baggage
  • travel delays
  • missed departures
  • personal liability
  • emergency assistance

Optional cover may also be available for winter sports, gadgets, cruises or business travel.

The key point is that each section normally has its own limits, conditions and exclusions.

1. Emergency Medical Expenses

Medical cover is one of the most important parts of travel insurance.

If you become ill or injured abroad, treatment can be expensive, particularly in countries where healthcare costs are high.

A policy may cover:

  • hospital treatment
  • emergency surgery
  • ambulance costs
  • doctor consultations
  • prescribed medication
  • repatriation to the UK if medically necessary

Some policies also pay additional travel or accommodation costs if you cannot return home as originally planned.

However, medical claims may be restricted if a pre-existing condition was not declared.

2. Cancellation Cover

Cancellation cover may reimburse non-refundable travel costs if you have to cancel your trip for a reason listed in the policy.

Possible covered reasons can include:

  • serious illness
  • injury
  • bereavement
  • certain family emergencies
  • redundancy in some circumstances
  • serious damage to your home

What usually does not count is simply changing your mind.

Likewise, deciding not to travel because you feel uncomfortable about a destination may not be covered unless the policy specifically includes that situation.

3. Curtailment Cover

Curtailment applies when you have already started your trip but need to return home early.

For example, you may need to end your holiday because:

  • you become seriously ill
  • a close relative has a medical emergency
  • your home is badly damaged

Depending on the policy, you may be able to claim for unused accommodation or travel costs.

4. Lost, Stolen or Damaged Baggage

Many travel insurance policies include baggage cover.

This can help with the cost of replacing:

  • clothing
  • luggage
  • personal belongings
  • travel documents

However, baggage claims often include a single-item limit.

So even if your overall baggage cover is £2,000, an expensive laptop or watch may only be covered up to a much lower amount.

Check:

  • overall baggage limit
  • single-item limit
  • valuables limit
  • excess

before relying on the policy.

5. Lost or Stolen Passports

Some travel insurance policies also cover passport-related costs.

This may include:

  • emergency travel documents
  • transport to an embassy or consulate
  • replacement-related expenses
  • extra accommodation in some circumstances

You may need to report the loss to the police or local authorities before making a claim.

6. Travel Delay Cover

Travel delay cover may pay compensation if your departure is delayed beyond a minimum period.

For example, a policy may start paying after:

  • 6 hours
  • 12 hours
  • 24 hours

The exact threshold varies.

Some policies provide a fixed payment, while others reimburse reasonable additional costs.

Travel delay cover is separate from any compensation rights you may have from an airline.

7. Missed Departure

Missed departure cover may help if you miss your flight or ferry because of circumstances outside your control.

Examples could include:

  • major public transport disruption
  • vehicle breakdown
  • serious road accident

Simply leaving home too late is unlikely to be covered.

The insurer may ask for evidence of what caused the delay.

8. Personal Liability

Personal liability cover can protect you if you accidentally injure someone or damage their property.

This may include certain legal costs or compensation claims.

However, exclusions often apply where the incident involves:

  • motor vehicles
  • business activity
  • deliberate acts
  • hazardous sports

9. Personal Accident Cover

Some policies include a fixed benefit if an accident causes a serious injury, permanent disability or death.

This is separate from emergency medical cover.

The benefit amount depends on the policy wording and the type of injury.

10. Emergency Assistance

Many insurers offer a 24-hour emergency assistance line.

This can help arrange:

  • medical treatment
  • hospital communication
  • emergency transport
  • repatriation
  • travel changes after a serious incident

For major medical claims, the insurer may require you to contact them as soon as reasonably possible.

Common Travel Insurance Exclusions

Understanding exclusions is just as important as understanding the cover itself.

A claim may fall under a broad section such as “medical expenses” or “cancellation” but still be excluded because of the circumstances.

Pre-Existing Medical Conditions

Pre-existing medical conditions are one of the most important areas to check.

Insurers may ask about:

  • diagnosed conditions
  • ongoing treatment
  • prescription medication
  • recent hospital visits
  • medical investigations

If you fail to declare a condition when required, a related claim could be rejected.

Some insurers provide cover after medical screening, sometimes for an additional premium.

Travelling Against Medical Advice

Policies commonly exclude claims where a traveller goes abroad against the advice of a doctor or other medical professional.

Travel for the main purpose of receiving medical treatment may also be excluded.

Alcohol and Drug-Related Incidents

Travel insurers may decline claims where alcohol or drugs materially contributed to the incident.

This does not necessarily mean any alcohol consumption invalidates the policy.

The exact wording matters.

High-Risk Sports and Activities

Standard policies may not automatically cover:

  • skiing
  • snowboarding
  • scuba diving
  • mountaineering
  • skydiving
  • certain water sports
  • competitive sports

Some insurers allow you to add specialist activity cover.

If your holiday includes adventurous activities, check the policy before travelling.

Unattended Belongings

Insurers may reject baggage claims where possessions were left unattended or unsecured.

For example:

  • valuables left on a beach
  • a phone left in an unlocked vehicle
  • luggage left unattended in a public place

Many policies also require theft to be reported to local police.

Valuables Above Policy Limits

A policy may have a generous overall baggage limit but a much lower single-item cap.

This is especially important for:

  • laptops
  • cameras
  • jewellery
  • watches
  • smartphones

If you are travelling with expensive items, check whether specialist cover is needed.

Known Events

Travel insurance generally protects against unforeseen events.

If you buy a policy after a problem is already known, related claims may not be covered.

For example, if a major disruption has already been publicly announced before you buy the policy, the insurer may treat it as a known event.

Government Travel Warnings

Policies may exclude travel to destinations where official government advice warns against travel.

Before travelling, check the latest Foreign, Commonwealth & Development Office guidance.

The exact impact depends on the policy wording.

Illegal or Reckless Behaviour

Claims connected to criminal activity or deliberate reckless behaviour may be excluded.

Travel insurance is not designed to protect against every consequence of unlawful conduct.

Natural Disasters

Cover for:

  • earthquakes
  • floods
  • hurricanes
  • wildfires
  • volcanic eruptions

varies by insurer.

Some policies include protection under cancellation or delay sections, while others require specific additional cover.

Airline or Supplier Failure

Not all policies cover the financial failure of:

  • airlines
  • tour operators
  • hotels
  • travel providers

Some policies offer scheduled airline failure or end-supplier failure cover, but this is not always standard.

Business Travel

A leisure policy may not automatically cover business activity.

If you are travelling for:

  • meetings
  • conferences
  • manual work
  • consultancy
  • professional services

check whether business travel is included.

Single-Trip vs Annual Travel Insurance

There are two main types of travel insurance.

Single-Trip Cover

Designed for one specific trip.

This may suit people who travel only occasionally.

Annual Multi-Trip Cover

Designed for multiple trips during a 12-month period.

This can be more convenient for frequent travellers.

However, annual policies usually limit the maximum duration of each individual trip.

Always check the maximum trip length.

European vs Worldwide Travel Insurance

Travel insurance is often divided into geographical zones.

Typical options include:

  • Europe
  • worldwide excluding certain countries
  • worldwide including the USA and Canada

Worldwide cover that includes countries with high healthcare costs may be more expensive.

Make sure every destination on your itinerary is included in the policy area.

How Much Cover Do You Need?

The right amount of cover depends on the type of trip.

Consider:

  • destination
  • trip cost
  • value of luggage
  • health needs
  • activities planned
  • trip duration

A weekend break in Europe may require different cover from a long-haul family holiday or extended backpacking trip.

What Should You Compare Before Buying Travel Insurance?

  • medical expense limit
  • cancellation cover
  • curtailment cover
  • baggage limit
  • single-item limits
  • valuables cover
  • excess
  • travel delay benefits
  • missed departure cover
  • personal liability
  • activity restrictions
  • medical screening rules
  • destination restrictions
  • maximum trip duration
  • emergency assistance

The best policy is not necessarily the cheapest one.

It is the policy that provides appropriate cover for your trip at a reasonable cost.

Why the Excess Matters

The excess is the amount you may need to pay towards a claim.

For example, if you make a £500 claim and the policy has a £100 excess, the insurer may pay £400.

Check whether the excess applies:

  • per claim
  • per person
  • per section

A low-cost policy with a high excess may offer less practical value than it first appears.

Is Cheap Travel Insurance Worth It?

Cheap travel insurance can be suitable in some cases, but price should not be the only factor.

A very low-cost policy may offer:

  • lower medical limits
  • higher excesses
  • more exclusions
  • lower baggage limits
  • fewer cancellation reasons

At the same time, paying more does not automatically guarantee better cover.

The objective is to compare what you actually get for the premium.

Final Thoughts

Travel insurance can provide important financial protection when something goes wrong before or during a trip.

But the value of a policy depends on the details.

Two policies may both advertise medical, baggage and cancellation cover while providing very different limits, exclusions and excesses.

Before buying, read the policy terms carefully and think about the risks most relevant to your trip.

You can compare travel insurance options and guides with WiT Money to review different types of travel cover and understand how policies may differ.

Knowing what travel insurance covers – and what it excludes – can help you choose a policy with fewer surprises if you ever need to make a claim.

Key Takeaways

  • Buying maid insurance early ensures compliance with Singapore regulations from day one
  • It protects employers from unexpected medical and liability costs
  • Domestic helpers benefit from proper medical coverage and security
  • Choosing a reliable provider like Income Insurance offers tailored protection

Introduction

Hiring a domestic helper is a big step for many households in Singapore. It often brings relief, better work-life balance, and a sense of support at home. But before the helper even steps through the door, there’s one thing that shouldn’t be left until the last minute, and that’s insurance.

Arranging insurance in Singapore for your helper before employment begins isn’t just a box to tick. It sets the tone for a safe, responsible working relationship. More importantly, it protects both the employer and the helper from the unexpected.

Why Timing Matters More Than You Think

It’s easy to assume insurance can wait until the helper arrives. After all, there’s paperwork, logistics, and maybe even a bit of excitement in the air. But delaying this step can lead to unnecessary risk.

Singapore regulations require employers to secure maid insurance before the helper starts work. This includes medical coverage and a security bond. Without it, employment simply can’t proceed legally.

More than compliance, early coverage means protection kicks in immediately. Imagine a helper falling ill shortly after arrival. Without insurance in place, the costs could land squarely on the employer. That’s not a position anyone wants to be in.

Protection For Both Sides Of The Door

Let’s break it down a little. When you buy maid insurance in Singapore, it’s not just about meeting a requirement. It’s about creating a safety net.

For employers, coverage helps manage hospital bills and unexpected medical expenses, while liability protection reduces financial strain from accidents. Security bonds also provide reassurance in case of unforeseen issues.

For helpers, access to healthcare without delay brings peace of mind, especially when adjusting to a new country. There’s also financial support available in case of serious illness or injury, which makes a real difference when it matters most.

It’s a two-way street. And honestly, that balance matters more than people realise.

Choosing The Right Insurance Partner

Not all policies are created equal. Some offer basic coverage, while others provide more comprehensive benefits that go beyond the minimum.

This is where Income Insurance stands out. Their maid insurance plans are designed with real-life situations in mind. From hospitalisation coverage to personal accident benefits, the protection feels practical, not just theoretical.

There’s also something reassuring about working with an established insurer. It’s like choosing a sturdy umbrella before the rain starts. You hope you won’t need it, but you’re glad it’s there when you do.

When you buy maid insurance in Singapore, it’s worth looking at coverage limits, inclusions, and how simple the claims process is. A thoughtful choice here can make a real difference later.

Starting On The Right Foot

First impressions matter. And yes, that includes how employment begins. Securing insurance early sends a clear message. It shows responsibility, care, and respect for the helper’s well-being.

There’s also a practical side. With insurance sorted, employers can focus on settling their helper into the household. No last-minute stress, no scrambling to meet requirements.

It’s a small step, but it sets the tone for everything that follows.

Conclusion

Buying maid insurance before employment begins isn’t just a legal necessity. It’s a smart, considerate decision that protects everyone involved. From covering medical expenses to ensuring peace of mind, early preparation goes a long way.

In the bigger picture, it reflects a commitment to safety and fairness. And that’s something every household can stand behind.

To ensure reliable coverage and a smooth start, contact Income Insurance today to buy their maid insurance plan.

For many young adults transitioning into the professional world, health insurance often feels like a distant concern, a line item on a budget meant for “later in life.” However, the landscape of healthcare is shifting. From the rising costs of private medical care to the unpredictability of sudden health setbacks, more individuals in their twenties and thirties are realizing that waiting until an emergency happens is a gamble they can no longer afford.

Consequently, the act of seeking out and comparing health insurance quotes has become a vital ritual in securing one’s financial and physical futures.

The Shift in Perspective

In the past, the “invincibility complex” governed much of the youth’s approach to healthcare. Many believed that their youth acted as a natural shield against significant medical expenses. Yet, modern lifestyle pressures and the increasing prevalence of chronic conditions among younger demographics have changed their outlook. Today’s young adults are more informed; they recognize that a single hospital stay or a specialized surgical procedure can wipe out years of savings.

By actively seeking health insurance quotes, they are taking a proactive stance. This process allows them to understand the market, identify what coverage is essential for their specific lifestyle, and ensure they are not overpaying for “fluff” they don’t need while securing protection against the high costs of private healthcare.

Understanding the Value Beyond the Premium

When young adults look for quotes, their focus is increasingly shifting from “What is the cheapest option?” to “What provides the most comprehensive value?” They understand that health insurance is not just about hospital bills; it is about access. Whether it is the ability to choose a preferred specialist, shorter waiting times, or access to private wards, the right plan offers a level of comfort and efficiency that public options may not always provide.

Moreover, the “early bird” advantage is a significant motivator. Securing a plan while they are young and healthy often leads to more affordable premiums and ensures that they are covered before any “pre-existing conditions” develop, which could complicate insurance applications later in life.

Article image

Integration with Modern Lifestyles

The digital savvy of this generation has also streamlined how they interact with insurance. They value platforms that offer transparency and ease of use. Comparing quotes online allows them to weigh benefits like outpatient care, dental coverage, and wellness programs in real-time. This empowerment through information ensures that their final choice is a calculated investment rather than a forced purchase.

A Partner in Lifelong Wellness: Why Raffles Shield A + RH is the Smart Move for Young Adults

As young adults narrow down their healthcare coverage options, they often look for insurers that offer more than just financial protection. Beyond processing claims, they value a trusted healthcare partner that supports their long-term well-being and provides access to quality medical care throughout different stages of life. This is where Raffles Health Insurance (RHI) and its Integrated Shield Plan, Raffles Shield, can add meaningful value.

Secure Coverage Early and Lock in Low Premiums

For young adults, securing coverage early can be particularly beneficial. As they are generally less likely to have pre-existing medical conditions, they may be able to obtain broader coverage before health issues arise. This helps provide protection against future medical expenses and reduces the risk of exclusions that could affect coverage later in life.Purchasing health insurance at a younger age can also be more cost-effective, as younger individuals are typically considered lower risk. By starting early with a plan such as the Raffles Shield A + Raffles Hospital (RH) Option, young adults can establish long-term healthcare protection while supporting their broader financial goals.

Because base premiums for this tier are highly affordable for those in their 20s, they can often be fully paid using your MediSave account, resulting in zero out-of-pocket cash layout.

Take the Next Step Toward Your Health Security

Securing your future begins with a simple conversation. To understand how the Raffles Shield A + RH plan can offer you a more affordable and integrated healthcare experience, review the options on the Raffles Shield Plans page and Connect with a Consultant Today.

Navigating the transition into retirement involves many major financial milestones, but few are as critical-or as confusing-as enrolling in Medicare. For many older adults, the system feels like alphabet soup, filled with strict deadlines, complex regulations, and an overwhelming array of choices.

Unfortunately, Medicare is not a forgiving program. A single misunderstanding or missed deadline can result in permanent financial consequences that track you for the rest of your life. To ensure you protect both your health and your retirement savings, it is vital to understand the landscape.

When mapping out your senior health insurance options, avoiding these five common, high-stakes Medicare mistakes should be your top priority.

1. Missing Your Initial Enrollment Period (IEP)

The most common-and expensive-mistake is simply missing the window to sign up. For most people, the Initial Enrollment Period (IEP) is a strict seven-month window that opens three months before the month you turn 65, includes your birthday month, and extends for three months after.

If you miss this window and do not qualify for a Special Enrollment Period (such as having qualifying coverage through an active employer), you will face the Medicare Part B late enrollment penalty. This penalty adds an extra 10% to your monthly Part B premium for every full 12-month period you were eligible but failed to enroll. Worst of all, this penalty is not a one-time fine; it is a permanent surcharge added to your premium for as long as you have Medicare.

2. Assuming Employer Coverage Always Exempts You From Penalties

Many people plan to work past age 65 and assume that because they have health insurance through their job, they can safely ignore Medicare enrollment. This is a half-truth that often leads to a financial trap.

Whether you can delay Medicare depends entirely on the size of your employer. If you work for a company with 20 or more employees, your group health plan is generally considered “creditable,” allowing you to delay Part B without penalty. However, if you work for a small business with fewer than 20 employees, Medicare automatically becomes your primary coverage at age 65, and your company plan becomes secondary. If you fail to sign up for Part B under a small employer, your company plan can refuse to pay your medical bills, and you will begin accumulating lifetime late-enrollment penalties. Always verify your plan’s status with your HR department.

3. Neglecting Part D Prescription Coverage (The 63-Day Rule)

Even if you do not take any regular medications when you turn 65, skipping Medicare Part D (prescription drug coverage) can be a massive financial error.

Medicare requires you to maintain creditable prescription drug coverage. If you go 63 or more consecutive days without it after your IEP ends, a late enrollment penalty will be calculated when you eventually do join a plan. The Part D penalty is 1% of the national base beneficiary premium multiplied by the number of full, uncovered months you went without it. Like the Part B penalty, this fee is added to your monthly premium for life. The smartest move is to enroll in a low-cost, baseline Part D plan immediately at 65 to “lock in” your coverage and avoid lifetime penalties.

4. Waiting Too Long to Buy a Medigap (Supplement) Plan

Medicare Supplement insurance, or Medigap, helps pay for the out-of-pocket costs that Original Medicare leaves behind, such as deductibles and the 20% coinsurance balance.

Your best opportunity to buy a Medigap policy is during your six-month Medigap Open Enrollment Period, which begins the month you are 65 or older and enrolled in Part B. During this specific window, you have “guaranteed issue rights.” This means private insurance companies cannot look at your medical history, deny you coverage, or charge you higher premiums due to pre-existing conditions. If you miss this window and try to buy a Medigap plan later, you will have to undergo medical underwriting. If you have chronic health issues, insurers can legally charge you exorbitant rates or deny you coverage entirely, locking you out of supplemental protection.

5. Blindly Letting Your Plan Auto-Renew Every Year

Medicare is not a “set-it-and-forget-it” system. Every autumn, from October 15 through December 7, Medicare hosts its Annual Election Period (AEP). This is your opportunity to review and change your coverage for the upcoming year.

Many beneficiaries make the mistake of letting their Medicare Advantage or Part D plans automatically renew without reviewing the upcoming changes. Insurance carriers adjust their formularies (the list of covered drugs), provider networks, deductibles, and copays every single year. A medication that cost $20 a month this year could be moved to a higher tier next year, or your primary care physician could leave the plan’s network. Ignoring the Annual Notice of Change (ANOC) sent by your carrier every September can leave you trapped in an incompatible, expensive plan for an entire year.

Medicare is an invaluable asset for your golden years, but its rules require careful navigation. By keeping a close eye on deadlines, confirming the rules of your current employer coverage, and actively reviewing your policies annually, you can secure robust healthcare coverage while keeping your hard-earned retirement savings safe from lifetime penalties.

Filing an insurance claim correctly determines how quickly and smoothly a resolution is reached. Every individual holds insurance as a safeguard, and activating that protection requires following a defined process with accuracy. Lucy Lukic have noted that policyholders who understand the filing sequence before an incident occurs are consistently better prepared when the need arises. Notification to the insurer must happen promptly, documentation must be accurate, and the chosen filing method must align with the nature of the claim being submitted.

Once the insurer receives notification, an assessment is initiated to verify the loss and review supporting evidence. Policyholders who maintain organised records move through this stage without unnecessary delay. The method used to file the claim plays a direct role in how efficiently that assessment proceeds, which is why selecting the appropriate channel matters as much as the content of the submission itself.

What filing methods are available?

The filing process runs through several stages, and each one carries weight.

  1. Incident documentation comes first. The moment something happens, evidence should be gathered. Photographs taken immediately hold far more detail than those taken the following day. Written accounts recorded promptly reflect accurate sequences of events. Official reports, where applicable, should be requested without delay. This stage is often underestimated, yet it forms the foundation on which everything else rests.
  2. Formal notification follows. The insurer must be contacted through the channel specified within the policy. The notification should cover the date, the nature of the incident, and an outline of what is being claimed. Vague or incomplete notifications slow the assessment before it has even properly begun.
  3. Claim form submission comes next, and this is where many policyholders lose time. Every section of the form must be completed. No figures should be estimated without supporting evidence behind them. Declared values need to be traceable. A partially completed form does not get assessed; it gets returned.
  4. Cooperation with the insurer’s assessor is a stage that catches people off guard. Requests for additional documents, inspections, or clarifications are standard. Responding to these quickly keeps the timeline intact. Delays at this point almost always extend the overall process by more than the delay itself would suggest.
  5. Reviewing the final determination is the last stage. The outcome issued by the insurer should be checked carefully against both the original submission and the active policy terms. Discrepancies at this point are far easier to address when the policyholder has maintained a clear record throughout.

Documents required throughout

Certain documents are requested across virtually every claim type, regardless of how or where the filing is made.

  • A fully completed claim form approved by the insurer.
  • Photographic or physical evidence gathered at the time of the incident.
  • Proof of ownership or verified value for each asset referenced in the claim.
  • Current policy document, along with any endorsements in effect at the time.
  • Written records of every exchange with the insurer from first contact onward.
  • Third-party reports or official statements where the incident involves external parties.

There are only a few causes for most delays. Mismatched declared values, incomplete submissions, and slow assessor responses. Neither of these is particularly difficult to avoid, nor do any require exceptional circumstances.

Ensuring that evidence is gathered early, filed through the right channel, submitted complete documentation, and stayed responsive throughout the process will make claims feel easier. It’s there when you need it. It’s all about filing correctly.

Introduction: Weather as a Defining Risk

Queensland’s climate is both a blessing and a challenge. While the state enjoys abundant sunshine and coastal beauty, it also faces recurring natural hazards such as cyclones, floods, and hailstorms. For strata schemes, these environmental realities make insurance not just a legal requirement but a critical resilience tool.

The Climate Challenge for Strata Schemes

Cyclones and Coastal Risks

Northern and coastal regions of Queensland are particularly vulnerable to cyclones. High winds and storm surges can cause extensive damage to shared property, making insurance coverage essential for recovery. Historical events, such as Cyclone Debbie in 2017, demonstrated how quickly communities can be disrupted and how costly rebuilding can be without adequate coverage.

Flooding and Urban Vulnerabilities

Urban centres like Brisbane face flood risks due to river systems and heavy rainfall. The 2011 floods highlighted the vulnerability of urban infrastructure, including multi-unit complexes. Strata schemes in flood-prone areas must account for these risks when selecting insurance policies, ensuring coverage extends to water damage and structural repairs.

Insurance as a Resilience Mechanism

Coverage Beyond Compliance

While legislation mandates insurance for common property, resilience requires going further. Comprehensive coverage ensures that strata schemes can recover quickly after climate events, protecting both property values and community stability. This includes considering optional add-ons such as flood or cyclone-specific coverage, which may not be automatically included in standard policies.

Financial Protection Against Extreme Events

Insurance provides financial protection against the escalating costs of climate-related damage. Without adequate coverage, owners could face crippling repair bills, undermining both individual investments and collective governance. For example, rebuilding after a cyclone can cost millions, far beyond the capacity of individual owners to manage.

Practical Strategies for Climate Resilience

Preventive Infrastructure

Investing in resilient infrastructure, such as flood barriers or cyclone-resistant materials, reduces risk and may influence insurance terms. Preventive measures demonstrate proactive governance and protect residents. Complexes that upgrade roofing materials or install stormwater management systems often see reduced claims, which can help stabilise premiums.

Risk Assessment and Planning

Bodies corporate should conduct regular risk assessments to identify vulnerabilities. Planning for climate risks ensures that insurance policies align with actual exposure. This may involve engaging engineers or risk consultants to evaluate structural resilience and recommend improvements.

Expanding Knowledge Resources

Understanding how strata insurance interacts with climate risks requires accessible information. Guidance on residential strata insurance obligations in Queensland’s climate-sensitive regions helps owners and managers make informed decisions.

The Role of Insurers in Climate Adaptation

Adjusting Premiums

Insurers often adjust premiums based on geographic risk profiles. Complexes in cyclone-prone or flood-prone areas may face higher costs, reflecting the increased likelihood of claims. This can create financial strain but also incentivises bodies corporate to invest in resilience.

Encouraging Resilient Practices

Some insurers reward proactive risk management, such as installing resilient materials or maintaining safety systems. These incentives encourage bodies corporate to invest in climate adaptation, aligning financial and environmental goals.

Long-Term Implications for Property Owners

Value Preservation

Adequate insurance ensures that properties can be repaired or rebuilt after climate events, preserving long-term value. For investors, this stability is crucial in maintaining rental yields and resale potential.

Market Confidence

Buyers and investors are increasingly aware of climate risks. Robust insurance coverage signals responsible governance and enhances market confidence in strata schemes. Complexes that demonstrate resilience often attract stronger demand, even in high-risk regions.

Conclusion: Insurance as Climate Infrastructure

In Queensland, strata insurance is more than compliance; it is climate infrastructure. By integrating resilience strategies, preventive measures, and comprehensive coverage, strata schemes can navigate the challenges of a climate-sensitive environment. For owners and investors, this approach ensures both compliance and long-term protection in a state where weather is a defining force.

Shipping decisions affect business trust. Package loss causes stress. Damage creates lasting disputes. Delays harm brand value. Risk grows during transit. Distance increases handling points. Value raises emotional stakes. Product type changes exposure. Protection becomes a business choice. The shipping insurance offers risk balance. Coverage reduces financial shock. Claims restore shipment confidence. Many sellers skip evaluation. Smart planning avoids regret. Real scenarios reveal timing. Protection suits specific conditions. Business maturity guides decisions. Easypost supports modern shipping workflows. Platforms simplify carrier access. Insight comes from experience. Understanding risk saves effort. Clarity helps shipping confidence. This guide explains moments. Decisions should feel informed. Context matters for protection needs.

High Value Shipments Need Protection

High value shipments attract attention. Theft risk increases naturally. Mishandling causes major losses. Replacement costs hurt cash flow. Customer trust weakens quickly. Luxury goods face greater risk. Electronics suffer fragile exposure. Jewelry draws unwanted interest. Art demands careful coverage. Insurance offsets unexpected loss. Claims process restores capital. Businesses ship fewer units. Each unit holds high worth. One incident impacts revenue heavily. Easypost tools assess value risk. Shipping data informs protection. Sellers gain pricing insight. Value based decisions reduce fear. Coverage suits premium orders. Confidence improves order fulfillment. Customers feel secure purchases. Brand reputation stays strong. Protection supports growth planning.

Long Distance Routes Increase Risk

Long routes involve many hands. Transfers raise damage chances. Customs checks add delays. Climate shifts affect packaging. Weather events disrupt schedules. International legs increase exposure. Domestic cross country routes strain handling. Time in transit extends risk. Tracking gaps cause uncertainty. Insurance protects during delays. Claims help manage disruptions. Businesses expand global reach. Distance should guide coverage. Easypost integrates tracking clarity. Visibility supports risk evaluation. Longer journeys demand foresight. Protection aligns with logistics complexity. Sellers maintain service promises. Customer expectations remain met. Confidence travels with packages. Loss impact feels reduced. Distance no longer intimidates growth.

Product Type Shapes Insurance Needs

Fragile goods break easily. Glass requires extra care. Perishables face spoilage risk. Fashion items suffer stains. Machinery parts incur dents. Product nature defines exposure. Standard coverage may fail. Specialized items need evaluation. Insurance adapts to category. Claims depend on item class. Packaging helps but limits exist. Easypost supports category insight. Shipping rules vary widely. Temperature control adds risk. Liquids leak during transit. Returns become costly events. Protection supports niche sellers. Unique products demand foresight. Risk planning saves resources. Customer satisfaction stays intact. Product fit guides coverage.

Conclusion

Shipping protection is strategic. Decisions rely on context. Value distance product type matter. Blanket choices waste resources. Smart evaluation improves outcomes. Businesses grow with confidence. Loss events feel manageable. Claims restore operational balance. Easypost empowers shipping clarity. Tools simplify complex choices. Sellers gain control. Customers trust delivery promises. Insurance fits specific moments. Protection supports sustainable logistics. Thoughtful planning reduces surprises. Shipping becomes predictable. Risk feels shared. Growth continues smoothly.

When it comes to growing wealth, returns matter — but what you keep after tax matters even more. That’s why australian tax efficient investing has become a core focus for both new and experienced investors. Australia has one of the most investor-friendly tax systems in the world, but the benefits only work when you know how to use them. Whether you invest for income, long-term growth, or retirement, understanding how the tax system interacts with your portfolio can genuinely boost your after-tax returns. Crucially, this blog will also help you understand how franking credits work so you can identify and select the best fully franked dividend stocks for your tax bracket and income goals.

In this guide, we break down how tax-efficient investing works, how franking credits influence your income, and how major ASX companies like ANZ and Telstra show the practical benefits. We’ll also explore important investment tax strategies australia investors often rely on — from superannuation to long-term dividends. All of these are essential parts of tax efficient investing.

Why Tax-Efficient Investing Matters in Australia

Australia’s tax rules shape investment outcomes more than most people realise. The country’s dividend imputation system — which includes franking credits — prevents “double taxation” on profits distributed by companies. Instead of paying tax twice (once at the company level and again at the investor level), investors receive a credit for tax already paid by the company.

This can dramatically reduce your tax bill. In lower tax brackets, the benefit is even more powerful because the franking credit can exceed your tax liability, leading to a cash refund. This structure is why many Australian investors prefer dividend-paying ASX stocks as part of their tax planning for investors australia strategy. This benefit is a major part of tax efficient investing.

Understanding Franking Credits: The Core of Tax-Efficiency

Before diving into practical examples, it helps to understand how franking works.

  1. Australian companies pay a 30% corporate tax.
  2. If they distribute dividends, they can attach franking credits equal to this tax.
  3. Investors include both the dividend and the credit in taxable income.
  4. The franking credit then acts as an offset against their personal tax.

This creates a system where the true tax rate on your dividends depends heavily on your personal marginal rate. This feature alone sits at the centre of most tax minimisation strategies australia investors use. It also plays a central role in tax efficient investing.

ANZ Group (ASX: ANZ) – Partially Franked Income

ANZ is one of the largest banks in the country, and like many financial institutions with global operations, its dividends are partially franked. ANZ dividends are often partially franked, typically around 60–80% depending on the year.

Why ANZ Dividends Are Partially Franked

ANZ earns a substantial share of its income outside Australia. Profits generated overseas are taxed in foreign jurisdictions — and foreign tax does not create Australian franking credits. This naturally limits the franking percentage.

What This Means for Tax-Efficient Investors

If you hold ANZ shares:

  1. Part of your dividend is tax-efficient (franked).
  2. Part is fully taxable (unfranked).

For investors in low or moderate tax brackets, ANZ’s partial franking still provides valuable offsets. For those in higher brackets, the credits reduce the difference between corporate tax and personal tax, improving the after-tax outcome.

Why ANZ Still Matters in Investment Tax Strategies

Banks like ANZ usually balance between dividends and occasional buybacks depending on their capital needs and restructure its balance sheet, but the dividend payout was maintained. This stability matters because:

  1. Steady income supports long-term compounding.
  2. Partial franking still improves net returns.
  3. Banks historically provide consistent dividend streams.

For investors building a resilient portfolio, ANZ can play an important role in diversified investment tax strategies australia. It also supports broader tax efficient investing goals.

Telstra Group (ASX: TLS) – Fully Franked Income Stream

Telstra remains one of Australia’s most popular dividend stocks — and a major reason is its fully franked dividends. The company’s FY2025 interim dividend was 100% franked, giving investors the full benefit of imputation credits. It is a key example of tax efficient investing in practice.

Why Fully Franked Dividends Matter

Fully franked dividends are the “gold standard” in australian tax efficient investing because:

  1. Investors receive the maximum franking credit per dollar.
  2. Low-income investors may receive refunds for unused credits.
  3. Higher-income investors still significantly reduce tax payable.

Telstra’s Moves Support Tax-Efficient Investors

Telstra has historically paid fully franked dividends and has often used share buybacks when cash flows are strong.

For long-term investors looking for reliable income, Telstra aligns perfectly with common tax minimisation strategies australia.

Smart Tax-Efficient Investing Strategies

Below are practical approaches commonly used in tax planning for investors australia — and they apply regardless of market cycles. These strategies are widely used in tax efficient investing.

1. Match Investments to Your Tax Bracket

Different dividend types have different advantages:

  1. Low-income investors often benefit most from fully franked dividends (e.g., Telstra) because unused franking credits may be refunded.
  2. High-income investors still gain value, though fully franked dividends simply reduce the tax gap.

This makes tax bracket awareness a critical part of investment tax strategies australia.

2. Use Dividend Reinvestment Plans (DRPs)

DRPs compound your wealth without requiring new capital. They are tax-efficient because:

  • You reinvest before spending the cash.
  • Your share count grows automatically.
  • Franked dividends continue working for you each year.

3. Think Long-Term

Frequent trading often realises capital gains prematurely. Long-term investing:

  1. Allows franking credits to accumulate.
  2. Helps maintain stable taxable outcomes.
  3. Reduces the paperwork burden at tax time.

Consistent holding periods also reduce CGT if you sell later with the 50% discount.

4. Use Superannuation for Maximum Tax Efficiency

Super funds are taxed at concessional rates, and in retirement phase, tax may drop to 0%. This means:

  1. Franking credits often result in refunds to the fund.
  2. Fully franked dividend stocks compound extremely efficiently.

This makes super one of the most powerful tax minimisation strategies australia investors can use.

5. Keep Clean, Accurate Records

For dividends, always record:

  1. Cash received
  2. Franking credits
  3. Franking percentage

Accurate records make tax efficient investing easier and more predictable.

Final Thoughts

Tax is an unavoidable part of investing, but it doesn’t have to eat into your returns. With the right approach to australian tax efficient investing — including understanding franking credits, choosing the right income stocks, making use of super, and planning long-term — you can meaningfully improve your after-tax wealth over time. This reinforces the value of tax efficient investing.

Many people get dental and vision insurance as part of their health coverage, but surprisingly, few make full use of it. Whether it’s missing routine checkups or overlooking coverage for preventive care, you could be leaving valuable benefits unused each year. Let’s discuss how you can make the most of your dental and vision insurance plans and ensure that every dollar you spend truly works for you.

Understanding What Your Plan Covers

The first step in maximizing your insurance benefits is knowing what’s included in your plan. Too many people sign up for coverage without reviewing the details. Dental and vision plans often cover preventive care, such as exams, cleanings, and screenings, at little to no cost. However, coverage for procedures like fillings, crowns, or prescription lenses can vary widely.

Take a close look at your plan summary. Which services are fully covered? Which ones require a copay or deductible? Knowing this information helps you plan treatments strategically throughout the year.

For instance, if your dental plan covers two cleanings annually, make sure you actually schedule both. It’s one of the easiest ways to protect your oral health and prevent costly problems later.

Schedule Preventive Care First

Preventive care is the foundation of both dental and vision health. Regular checkups allow your dentist or eye doctor to catch potential issues early—often before they become serious or expensive. But here’s the thing: preventive visits are already built into your insurance plan, and not using them means you’re wasting paid benefits.

Let’s discuss an example. If your dental insurance offers two free cleanings and one exam per year, skipping them means paying for insurance that you’re not using. The same goes for vision coverage—if your plan includes an annual eye exam, schedule it even if your eyesight feels fine. Many eye conditions, like glaucoma or cataracts, develop slowly and without noticeable symptoms at first.

Take Advantage of Covered Screenings and X-Rays

Your insurance often covers diagnostic services like dental X-rays or vision screenings. These are not just routine procedures—they’re early detection tools. X-rays can reveal cavities between teeth, bone loss, or infections you wouldn’t notice otherwise. Vision screenings, meanwhile, can detect eye diseases or changes in vision that may signal other health concerns like diabetes or high blood pressure.

Instead of waiting for a problem to arise, use these preventive diagnostics to catch potential issues early. It’s both cost-effective and better for your long-term health.

Use Your Benefits Before They Expire

Most dental and vision plans operate on a yearly cycle. If you don’t use your benefits by the end of the year, they usually don’t roll over. This means any unused cleanings, exams, or allowances for glasses and contact lenses simply disappear.

Have you checked how much of your annual allowance remains? Let’s discuss this—many people realize too late that they could’ve replaced old lenses or taken advantage of orthodontic discounts before the year ended. Schedule appointments early to avoid the year-end rush at clinics and optical centers.

Maximize Your Vision Allowance for Eyewear

If your vision insurance includes an allowance for glasses or contact lenses, don’t let it go unused. Even if your prescription hasn’t changed, you can use your benefit to get a backup pair of glasses, prescription sunglasses, or specialty lenses for computer use.

Ask your optician about all eligible options under your plan. Many vision insurance policies also offer discounts on lens coatings, anti-glare treatments, or designer frames. Using your allowance wisely means you’ll enjoy both comfort and style—without paying extra.

Coordinate Your Benefits with Family Members

If your spouse or children are also covered under your dental or vision plan, coordinate appointments to make sure everyone benefits. Many family plans have shared limits or annual maximums, and it’s easy to forget to schedule appointments for dependents.

By keeping a record of each member’s usage, you can ensure no one misses out on their covered services. Plus, scheduling visits together can save time and help you stay consistent with preventive care.

Combine Insurance with Flexible Spending Accounts (FSAs)

If your employer offers a Flexible Spending Account (FSA), use it to supplement your dental and vision expenses. FSAs allow you to set aside pre-tax income for qualified medical costs, which can include copays, deductibles, or even new eyewear.

Here’s a smart strategy: use your insurance benefits first, then pay the remaining balance with your FSA funds. This dual approach helps you stretch your dollars and reduce your taxable income at the same time.

Plan Major Procedures Strategically

Some dental procedures—like root canals, crowns, or orthodontics—can be expensive. If your plan has an annual maximum benefit (say, $1,500), you can schedule treatments across two benefit years to reduce out-of-pocket costs. For instance, start a procedure in December and complete it in January after your benefits renew.

Let’s discuss another example: if you know your child might need braces, talk to your dentist or orthodontist about phased treatment. They can help plan appointments in a way that aligns with your insurance coverage to maximize savings.

Ask Your Provider for Cost Estimates

Before undergoing any procedure or treatment, always ask your dental or vision provider for a cost estimate. This helps you understand how much the insurance will cover and what portion you’ll need to pay. Many clinics can even send a pre-authorization request to your insurance company to confirm coverage in advance.

This proactive step eliminates financial surprises and allows you to make informed decisions about your care.

Stay In-Network When Possible

Most insurance plans have preferred networks of dentists and eye doctors. Staying within this network usually means lower out-of-pocket costs, as providers have agreed-upon rates with your insurer. Going out-of-network can significantly increase what you pay for services.

If you’re unsure whether your provider is in-network, check your insurer’s website or call their customer service. Sometimes, even switching to a nearby clinic within the network can make a big difference in annual savings.

Re-Evaluate Your Plan Each Year

Insurance needs change over time. If you find that your current plan doesn’t fit your lifestyle—maybe you need more frequent cleanings, or your child just got glasses—review other plan options during open enrollment. A slightly higher premium might offer greater long-term value if it reduces your out-of-pocket costs on recurring treatments.

Re-evaluating your plan annually ensures you’re not overpaying for benefits you don’t use or missing coverage that could help you.

Final Thoughts

Your dental and vision insurance plans are more than just paperwork—they’re tools to help you maintain long-term health and prevent costly treatments down the road. The key is using them strategically and consistently.

From scheduling preventive care and utilizing allowances to coordinating family benefits and staying in-network, small actions can help you get the most value from your coverage. So don’t wait for problems to appear—use your benefits proactively.

After all, taking care of your smile and vision isn’t just about looking good—it’s about protecting two of your most valuable assets: your health and your confidence.

Life is a series of unfolding events where dreams, desires, and ambitions arise. Maybe this is the stage of buying your first home, starting a family, or preparing for a shining retirement. Every phase presents special challenges and opportunities. Intensive consideration is given to insurance in almost every life equation. Yet most regard insurance as just one expense rather than a safety net if tailored to their given needs.

Why It Is Essential to Have Customized Insurance Plans

An insurance package is more than just a policy to the truly customized; it is the story of a person. We all have different needs, and one-size-fits-all solutions will not do for anyone. Life events such as marriage or starting a business modify one’s insurance requirements. So, when a custom-made plan is set up, the client is protected from being underinsured during the transition. On top of that, a generic benefit package may leave gaps in coverage, putting you in a vulnerable position and affecting your financial well-being. By customizing your plan, you are dealing with anything you want to defend against in the areas most important to you.

One other thing, in time, customized plans may actually save you money. They take a closer look at what really matters to you, whereas unimportant additional coverage is less of an issue. Achieving peace of mind through insurance is priceless. You and your loved ones can pursue your dreams without fearing unforeseen events that will shape life toward your ways.

Know Your Life Goals; Know Your Insurance Needs

The life goals that one cherishes end up shaping all his decisions, including buying insurance. When buying a property, getting married, having kids, and starting a business, all require a life of dreams but simultaneously generate needs. For instance, if you work toward homeownership, mortgage protection, and homeowner’s insurance become imperative. These insurance plans actually protect your investment and sustain your long-term vision.

However, starting a family shifts the priority to health insurance and life coverage. Having the assurance that your loved ones would be taken care of provides you with the finest peace of mind during the onset of this new chapter. Even educational or career objectives might come into play when opting for disability or business liability insurance. Every kind of goal calls for a specific solution that can guarantee utmost security and flexibility. By acknowledging what actually matters to you-whether it be financial freedom or setting up a legacy-generational wealth, you can line up your insurance buying with these goals.