Author

Clare Louise

Browsing

An audit does not have to be slow. Most of the delay in an SME audit comes from the company’s side, in the state of its records. A slow audit is more than a nuisance, because it can push you past your filing deadline. The best audit services singapore can move quickly, but only when your company is ready for them. Here are the issues that can slow an audit down, and what you can do to keep your own on track.

Incomplete or Disorganised Records

An audit is built on evidence, so the first delay usually comes from records that are hard to find. When invoices, contracts, and statements are scattered or missing, the auditor has to stop and ask for them. Every request adds a wait for your reply. The auditor cannot sign off on what they cannot see. A complete, well-organised set of records is the biggest thing that keeps an audit moving.

Accounts That Are Not Reconciled

Auditors expect your accounts to be reconciled before they start. If your bank balance does not match the ledger, or your control accounts do not agree, the audit stops while the differences are chased down. Unreconciled accounts also raise doubts that lead to more testing. Reconciling your bank, debtors, and creditors before the auditor arrives removes one of the most common causes of delay.

Missing Supporting Schedules

Behind the main figures are the schedules that explain them. Auditors will ask for a fixed asset listing, a breakdown of your debtors and creditors showing how long each amount has been outstanding, and details of your prepayments and accruals. These schedules tie your totals back to the detail behind them. If they are not ready, the audit team has to wait while someone prepares them, so having them done in advance lets the work move straight to checking.

Transactions No One Can Explain

Every audit brings up entries that need an explanation, and it is the unanswered ones that take up the most time. A large one-off payment, a round-sum transfer, or a balance owed by a director will draw a query. Related-party dealings, such as loans between the company and its directors, get particular attention. If no one can explain them quickly, the item stays open, so noting anything unusual when it happens saves time later.

Waiting on Outside Confirmations

Some delays come from outside your company. Auditors send confirmations to banks, customers, and suppliers. These can take time to come back, with banks in particular often taking a couple of weeks. A stock count that was not done, or not observed by the auditor, can delay the whole audit. Arranging these early, and telling the auditor about a stock count in advance, keeps them from stalling everything else.

Timing and the Audit Busy Season

In Singapore, most companies close their books on 31 December, which makes the first few months of the year a busy season for audit firms. If you hand over messy records during that window, your audit joins a long queue and waits its turn. Getting your file ready early, before the rush, often means a faster turnaround. Koh Management prepares SME accounts and audit files so the records are clean and complete before the auditor begins.

Keeping Your Audit on Track

A smooth audit is mostly decided before it starts. Agree a timeline with your auditor, prepare your reconciliations and schedules, and gather the year’s records in one place. During the audit, try to answer queries within a day or two so they do not pile up. A clean file can also lower your fee, since the cost of an audit often reflects how much work the records need.
Businesses in Stuttgart can reduce pressure created by late payments from customers by enhancing their processes of billing customers and following up. Having an effective payment system makes it easier to build relationships with customers and leaves room for growth and investing in marketing efforts.

Set Clear Payment Terms

Payment terms need to be specified prior to the start of a sale or a project. The contract or an invoice must state the due date of the payment, possible ways of payment, and any other information concerning the overdue amount. If the process is clear and simple, customers will be able to make payments on time.

Send Accurate Invoices Quickly

Invoices need to be issued right after the delivery of a product or performance of services. Every invoice should contain information on the client, invoice number, payment term, description of services, and banking information. The use of software that manages invoicing can simplify the whole process.

Create a Consistent Reminder Process

It is important not to wait for weeks in order to remind customers about unpaid bills. Friendly reminders prior to the due date will help to avoid the delay and in case of overdue payments professional follow up must be done immediately. It is possible to use such approach as an instrument of showing that payment deadlines are taken seriously.

In case of problematic invoices, the service of Inkassodienstleister aus Stuttgart can help to focus on selling and promoting services without worrying about invoices.

Connect Payment Management With Customer Experience

An efficient payment management system needs to be integrated in the customer experience process. Customer Relationship Management (CRM) systems can provide information about the status of invoices, customer communication history, and possible behavior concerning payment and help to find reliable customers and minimize risks of marketing campaign.

Offer Convenient Payment Options

If paying becomes easy, chances for receiving payments on time grow significantly. Such convenient options as payment links, online banking, mobile invoicing, and automated payment can reduce the effort needed for making payments.

Review Payment Patterns Regularly

The firm should continuously evaluate and examine which clients always make their payments on time and for how long their invoices stay unpaid. This kind of analysis will give the management enough information about whether it is necessary to change the conditions of payment, ask for the deposit, or limit credit in order to improve accounts receivable processes.

Build a Healthier Revenue Cycle

Not only accounting but also finances become more stable and have regular cash flows due to faster payment. Those companies in Stuttgart that have good policies combined with proper invoicing, reminders, payment methods, and continuous customer analysis may secure their revenues without ruining the business relations. Thus, a strong foundation for the marketing and expansion is ensured.

Florida’s growing population brings growing demand for behavioral care. Acadia Healthcare and Orlando Health are answering part of that need with a new hospital planned for the region.

Acadia Healthcare is the largest stand-alone behavioral health company in the country, and it’s chaired by Reeve Waud, who founded Waud Capital Partners. The Orlando Health project is one piece of a wider expansion push.

A 144-Bed Facility

The joint venture calls for a 144-bed hospital, part of Acadia’s 2026 pipeline. A facility that size can serve a large number of patients once it reaches full operation.

Behavioral hospitals of 144 beds have become something of a template for Acadia. The size is big enough to matter for a region yet still manageable to staff and run well, which helps a new site find its footing. It also leaves room to add services over time as the community’s needs become clearer. Behavioral care rarely stands still, and a flexible design lets the hospital adapt.

Meeting Regional Demand

Central Florida has added residents quickly, and behavioral care hasn’t always kept pace. A new inpatient hospital gives the area more room to treat patients who might otherwise wait or travel far for help.

Partnering with Orlando Health gives the project local roots. The health system already serves the community and carries a trusted name, and that helps patients and referring doctors feel confident in the new facility. Shorter travel times can be the difference between a patient getting timely care and going without. A growing population tends to bring rising demand for behavioral services, and the new hospital is built to absorb it.

Part of a Pattern

The Orlando venture isn’t a one-off. It sits alongside partnerships in Boston, Iowa, and elsewhere, all built on the same joint-venture blueprint.

That repeatable model is what lets Acadia Healthcare expand on several fronts at once. For Reeve Waud, who’s spent a career backing scalable approaches, the Florida project is another example of a formula that keeps working across very different markets. Repeat success also makes the next partner easier to sign, since health systems can point to hospitals already up and running.

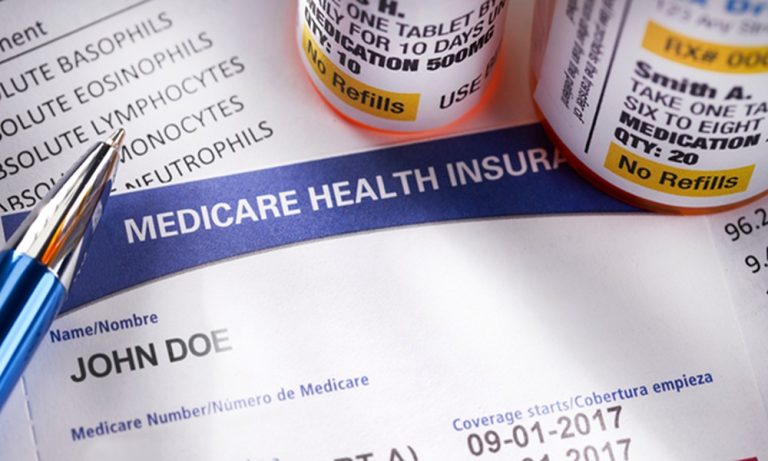
Navigating the transition into retirement involves many major financial milestones, but few are as critical-or as confusing-as enrolling in Medicare. For many older adults, the system feels like alphabet soup, filled with strict deadlines, complex regulations, and an overwhelming array of choices.

Unfortunately, Medicare is not a forgiving program. A single misunderstanding or missed deadline can result in permanent financial consequences that track you for the rest of your life. To ensure you protect both your health and your retirement savings, it is vital to understand the landscape.

When mapping out your senior health insurance options, avoiding these five common, high-stakes Medicare mistakes should be your top priority.

1. Missing Your Initial Enrollment Period (IEP)

The most common-and expensive-mistake is simply missing the window to sign up. For most people, the Initial Enrollment Period (IEP) is a strict seven-month window that opens three months before the month you turn 65, includes your birthday month, and extends for three months after.

If you miss this window and do not qualify for a Special Enrollment Period (such as having qualifying coverage through an active employer), you will face the Medicare Part B late enrollment penalty. This penalty adds an extra 10% to your monthly Part B premium for every full 12-month period you were eligible but failed to enroll. Worst of all, this penalty is not a one-time fine; it is a permanent surcharge added to your premium for as long as you have Medicare.

2. Assuming Employer Coverage Always Exempts You From Penalties

Many people plan to work past age 65 and assume that because they have health insurance through their job, they can safely ignore Medicare enrollment. This is a half-truth that often leads to a financial trap.

Whether you can delay Medicare depends entirely on the size of your employer. If you work for a company with 20 or more employees, your group health plan is generally considered “creditable,” allowing you to delay Part B without penalty. However, if you work for a small business with fewer than 20 employees, Medicare automatically becomes your primary coverage at age 65, and your company plan becomes secondary. If you fail to sign up for Part B under a small employer, your company plan can refuse to pay your medical bills, and you will begin accumulating lifetime late-enrollment penalties. Always verify your plan’s status with your HR department.

3. Neglecting Part D Prescription Coverage (The 63-Day Rule)

Even if you do not take any regular medications when you turn 65, skipping Medicare Part D (prescription drug coverage) can be a massive financial error.

Medicare requires you to maintain creditable prescription drug coverage. If you go 63 or more consecutive days without it after your IEP ends, a late enrollment penalty will be calculated when you eventually do join a plan. The Part D penalty is 1% of the national base beneficiary premium multiplied by the number of full, uncovered months you went without it. Like the Part B penalty, this fee is added to your monthly premium for life. The smartest move is to enroll in a low-cost, baseline Part D plan immediately at 65 to “lock in” your coverage and avoid lifetime penalties.

4. Waiting Too Long to Buy a Medigap (Supplement) Plan

Medicare Supplement insurance, or Medigap, helps pay for the out-of-pocket costs that Original Medicare leaves behind, such as deductibles and the 20% coinsurance balance.

Your best opportunity to buy a Medigap policy is during your six-month Medigap Open Enrollment Period, which begins the month you are 65 or older and enrolled in Part B. During this specific window, you have “guaranteed issue rights.” This means private insurance companies cannot look at your medical history, deny you coverage, or charge you higher premiums due to pre-existing conditions. If you miss this window and try to buy a Medigap plan later, you will have to undergo medical underwriting. If you have chronic health issues, insurers can legally charge you exorbitant rates or deny you coverage entirely, locking you out of supplemental protection.

5. Blindly Letting Your Plan Auto-Renew Every Year

Medicare is not a “set-it-and-forget-it” system. Every autumn, from October 15 through December 7, Medicare hosts its Annual Election Period (AEP). This is your opportunity to review and change your coverage for the upcoming year.

Many beneficiaries make the mistake of letting their Medicare Advantage or Part D plans automatically renew without reviewing the upcoming changes. Insurance carriers adjust their formularies (the list of covered drugs), provider networks, deductibles, and copays every single year. A medication that cost $20 a month this year could be moved to a higher tier next year, or your primary care physician could leave the plan’s network. Ignoring the Annual Notice of Change (ANOC) sent by your carrier every September can leave you trapped in an incompatible, expensive plan for an entire year.

Medicare is an invaluable asset for your golden years, but its rules require careful navigation. By keeping a close eye on deadlines, confirming the rules of your current employer coverage, and actively reviewing your policies annually, you can secure robust healthcare coverage while keeping your hard-earned retirement savings safe from lifetime penalties.

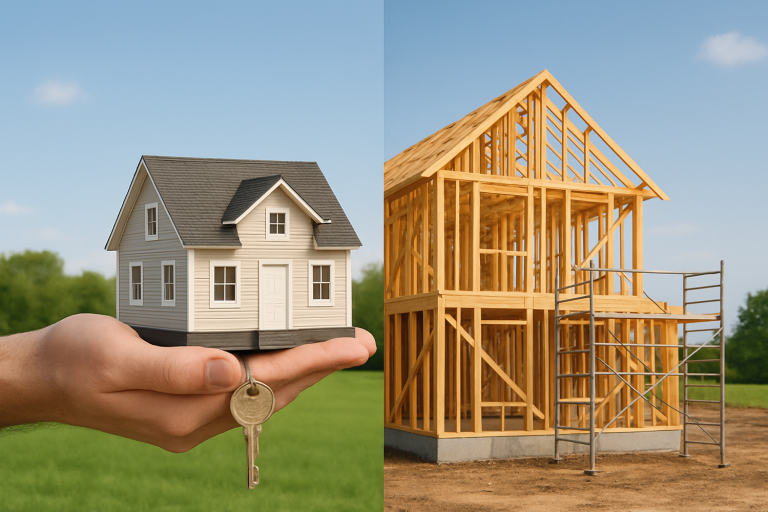
Building a home or financing a large-scale construction project requires a very different type of funding than buying an existing property. This is where construction loans come into play. These specialized financing solutions are designed to support projects from the ground up, providing flexibility, staged funding, and tailored repayment structures that align with the construction process.

In this comprehensive guide, we’ll explore how construction loans work, their benefits, types, requirements, and how to choose the right lender for your needs.

What Are Construction Loans?

Construction loans are short-term, high-interest loans used to finance the building or renovation of a property. Unlike traditional mortgages that provide a lump sum upfront, these loans release funds in stages—often referred to as “draws”—as construction milestones are completed.

This structure ensures that funds are used efficiently and that lenders maintain oversight of the project’s progress.

How Construction Loans Work

The process behind construction loans is unique compared to standard home financing:

• The borrower submits detailed building plans, budgets, and timelines
• The lender evaluates the feasibility of the project
• Funds are released in phases based on construction progress
• Interest is typically paid only on the amount drawn
• Once construction is complete, the loan is either repaid or converted into a traditional mortgage

This staged approach minimizes risk for both the borrower and the lender while ensuring accountability throughout the project.

Types of Construction Loans

There are several types of construction loans, each tailored to different needs:

Construction-to-Permanent Loans

These loans convert into a traditional mortgage once construction is complete. They are ideal for borrowers who want a seamless transition from building to long-term financing.

Stand-Alone Construction Loans

These are short-term loans that must be paid off or refinanced into a mortgage after construction ends. They offer flexibility but may involve additional closing costs.

Owner-Builder Loans

Designed for individuals who plan to act as their own contractor, these construction loans often require proof of experience and strong financial credentials.

Renovation Construction Loans

Used for remodeling or major upgrades, these loans combine the cost of purchase and renovation into a single financing solution.

Key Benefits of Construction Loans

Choosing construction loans offers several advantages:

• Flexible funding aligned with project milestones
• Interest payments only on funds used
• Customization for unique building projects
• Potential for higher property value upon completion
• Greater control over design and materials

For many borrowers, these benefits outweigh the complexities associated with construction financing.

Requirements for Construction Loans

Qualifying for construction loans can be more demanding than traditional mortgages. Lenders typically look for:

• Strong credit score (often 680 or higher)
• Detailed construction plans and timelines
• Licensed builder or contractor agreement
• Solid down payment (usually 20%–30%)
• Proof of income and financial stability

Because of the higher risk involved, lenders require thorough documentation and careful planning.

Understanding the Draw Schedule

A key feature of construction loans is the draw schedule. This outlines when and how funds are released during the project.

Typical stages include:

• Land purchase or site preparation
• Foundation completion
• Framing and structural work
• Interior and exterior finishing
• Final inspection and completion

Each stage must be verified before funds are released, ensuring the project stays on track.

Interest Rates and Costs

Interest rates for construction loans are generally higher than traditional mortgages due to the increased risk. However, borrowers benefit from paying interest only on the funds used rather than the full loan amount.

Additional costs may include:

• Inspection fees
• Permit and administrative costs
• Closing fees
• Contingency reserves

Understanding these costs upfront helps prevent unexpected financial strain during construction.

Choosing the Right Lender

Selecting the right lender is critical when applying for construction loans. Experienced lenders understand the complexities of construction financing and can guide borrowers through every stage of the process.

A trusted provider like California Construction Loans offers tailored solutions, ensuring that each project receives the right financial structure and support. Working with a specialized lender can significantly improve the chances of a smooth and successful construction journey.

Common Mistakes to Avoid

When dealing with construction loans, avoiding common pitfalls is essential:

• Underestimating project costs
• Choosing inexperienced contractors
• Ignoring contingency planning
• Failing to understand loan terms
• Delays due to poor project management

Proper preparation and expert guidance can help mitigate these risks.

Is a Construction Loan Right for You?

Construction loans are ideal for individuals and developers who want to build custom properties rather than purchase existing ones. They provide flexibility and control but require careful planning and financial discipline.

If you have a clear vision, a reliable contractor, and a solid financial foundation, this type of loan can be a powerful tool to bring your project to life.

Final Thoughts

Navigating the world of construction loans may seem complex, but with the right knowledge and support, it becomes a manageable and rewarding process. These loans empower borrowers to create tailored spaces that meet their exact needs while maintaining financial structure and oversight.

Whether you’re building a dream home or investing in a new development, understanding how construction loans work is the first step toward turning your vision into reality.

In the evolving landscape of digital finance, on-chain analytics have emerged as a pivotal tool for investors seeking transparency and informed decision-making. By leveraging blockchain’s inherent openness, these analytics provide real-time insights into market behaviors, enabling both institutional and retail investors to assess opportunities and risks with unprecedented clarity.

Filename: onchain-analytics-note
Alt Text: Person writing notes on a piece of paper while analyzing data
Caption: An investor takes notes during on-chain data analysis to evaluate market behavior and digital asset risks.

Understanding On-Chain Analytics

On-chain analytics involve the examination of blockchain data to extract meaningful patterns and trends. Unlike traditional financial systems, where data is often siloed and delayed, blockchain offers a transparent and immutable ledger of all transactions. This openness allows for the analysis of various metrics, such as transaction volumes, wallet activities, and smart contract interactions, providing a comprehensive view of market dynamics.

For instance, platforms like Glassnode and CryptoQuant offer dashboards that track metrics such as active addresses, exchange inflows and outflows, and miner behaviors. These insights can indicate market sentiment, potential price movements, and liquidity trends, aiding investors in making data-driven decisions.

Enhancing Investment Awareness

The transparency afforded by on-chain analytics empowers investors to move beyond speculative trading towards informed investment strategies. By analyzing wallet behaviors, investors can identify accumulation or distribution phases, signaling potential bullish or bearish trends. Additionally, monitoring smart contract activities can reveal emerging decentralized applications (dApps) gaining traction, presenting early investment opportunities.

Moreover, on-chain data can aid in identifying anomalies or potential fraudulent activities. For example, sudden spikes in transaction volumes or unusual token movements can serve as red flags, prompting further investigation. This proactive approach to risk assessment is particularly valuable in the volatile crypto market.

Institutional Adoption and Regulatory Support

Institutional investors are increasingly recognizing the value of on-chain analytics in navigating the digital asset space. According to EY-Parthenon research, institutions believe in the long-term value of blockchain and digital assets, with allocations to digital asset-related products expected to increase.

Regulatory bodies are also acknowledging the importance of blockchain transparency. The UK government, for instance, has introduced draft legislation aimed at strengthening regulation of the cryptocurrency sector to protect consumers and enhance investor confidence. Such regulatory clarity fosters a more secure environment for investment and innovation.

The Role of Analytics Platforms

As the digital asset ecosystem continues to mature, a wide range of specialized platforms have emerged to support deeper visibility into blockchain activity. These on-chain analytics tools are now essential for stakeholders across the digital finance landscape – from institutional investors to digital asset management consultants – who rely on data-driven insights to guide strategic decisions and client advisories.

  • Glassnode has positioned itself as a leading provider of blockchain intelligence, offering comprehensive metrics that span across network health, user activity, liquidity trends, and market cycles. It delivers real-time insights on key indicators such as the number of active addresses, HODL waves, and net realized profit/loss – all of which can help identify behavioral patterns in Bitcoin and Ethereum holders. For example, Glassnode’s exchange balance metrics have been widely cited during periods of heavy accumulation or selloffs, helping investors understand whether assets are moving toward cold storage or into trading environments.
  • CryptoQuant complements this analytical landscape with a strong focus on centralized exchange behavior, miner flows, and macro-level sentiment indicators. The platform tracks inflows and outflows from major exchanges, helping investors assess whether whales are positioning for market movements. Its miner data – such as miner reserves and outflows – provides a unique window into supply-side pressure. For instance, a sudden uptick in miner outflows might indicate sell-side activity that could impact price dynamics in the short term, which is critical intelligence for crypto asset management professionals.
  • IntoTheBlock adds another layer of intelligence by applying artificial intelligence and machine learning algorithms to blockchain datasets. Its suite of indicators includes “In/Out of the Money,” which analyzes wallet profitability at different price levels, as well as concentration metrics that track the percentage of tokens held by top addresses. These insights are particularly valuable when evaluating altcoin investment options, as they help investors assess token distribution and potential vulnerability to price manipulation or illiquidity.

Together, these platforms serve as an indispensable toolkit for a broad array of digital asset stakeholders. Digital assets consulting professionals leverage these resources to perform comparative market assessments, uncover adoption trends, and evaluate project fundamentals. For portfolio management consultants, access to accurate on-chain signals supports enhanced investment analysis and portfolio management, enabling clients to better understand the timing, scale, and risk level of various digital asset positions.

Whether it’s a stablecoin investment consultant reviewing DeFi protocol health, or a real world DeFi investment consultant assessing tokenized cash flows from RWAs (real-world assets), these analytics platforms have become vital in translating blockchain transparency into actionable investment intelligence.

Addressing Market Skepticism

Despite the advancements in on-chain analytics, skepticism persists regarding the reliability and applicability of blockchain data. However, the integration of these analytics into compliance and regulatory frameworks is mitigating such concerns. Platforms like Chainalysis and Elliptic assist in tracking illicit activities, ensuring that blockchain ecosystems remain secure and trustworthy.

Article image

Furthermore, the adoption of standardized data practices, as advocated by organizations like the World Economic Forum, is enhancing the credibility of on-chain analytics. By aligning blockchain data with traditional financial reporting standards, these efforts are bridging the gap between decentralized and centralized financial systems.

Explore the Future of Digital Assets

Kenson Investments invites informed market participants to deepen their understanding of blockchain, digital assets, and evolving investment structures. Through accessible research, thought leadership, and market-focused education, Kenson Investments empowers institutions and startups alike to navigate digital finance with confidence and clarity.

About the Author
This content was written by a contributor focused on emerging trends in blockchain finance, digital asset education, and institutional market adoption. With a commitment to clarity over hype, the author explores how technology, policy, and data intersect to shape the future of decentralized finance and capital markets.

Disclaimer: The information provided on this page is for educational and informational purposes only and should not be construed as financial advice. Crypto currency assets involve inherent risks, and past performance is not indicative of future results. Always conduct thorough research and consult with a qualified financial advisor before making investment decisions.

“The crypto currency and digital asset space is an emerging asset class that has not yet been regulated by the SEC and US Federal Government. None of the information provided by Kenson LLC should be considered as financial investment advice. Please consult your Registered Financial Advisor for guidance. Kenson LLC does not offer any products regulated by the SEC including, equities, registered securities, ETFs, stocks, bonds, or equivalents”

Financial transparency is crucial for trust and accountability. To ensure this, you rely on the expertise of certified public accountants. Their work builds the foundation for clear and honest financial reporting. A CPA in Oakland, CA can play a key role in helping you achieve this level of transparency. They track every penny, ensuring your accounts are accurate and reliable. By doing so, they prevent any missteps that could lead to financial pitfalls. Their precise work guides you in making informed financial choices that strengthen your financial standing. This guidance reduces risks, making your financial dealings safer and more secure. With a CPA’s support, you gain a clearer view of your financial health. This clarity is essential for planning, budgeting, and strategic growth. Trust the expertise of a certified public accountant to help you achieve and maintain financial transparency. It all begins with choosing a qualified professional.

The Role of CPAs in Financial Transparency

A Certified Public Accountant acts as a financial guide. You trust their skills to ensure your finances are in order. CPAs review and refine your financial records, leaving no room for error. Their responsibility is to ensure that the financial information you rely on is accurate. When you work with a CPA, you can expect transparency and honesty in all financial dealings.

One key aspect of a CPA’s role is auditing. Through careful examination of your financial records, they verify the accuracy of your financial statements. According to the American Institute of CPAs, audits help prevent errors and fraud, providing you with confidence in the integrity of your finances. This process is fundamental to maintaining transparency and trust in your financial reports.

Benefits of Financial Transparency

Achieving financial transparency offers several benefits:

  • Trust Building: Transparent financial reports build trust among stakeholders.
  • Improved Decision-Making: Clear financial information aids in making informed decisions.
  • Risk Reduction: Transparency helps identify and mitigate financial risks.

Trust is essential for any business. When you maintain transparent financial records, you strengthen your relationships with partners, investors, and customers. With clear financial information, you find decision-making easier and more effective, leading to better business outcomes.

Why Choose CPA Services?

CPAs bring extensive knowledge to your financial management. They offer services such as tax preparation, financial planning, and auditing. Each service contributes to ensuring financial transparency, making them indispensable to your business.

When you choose a CPA, you benefit from their expertise and commitment to ethical practices. Their training and certification ensure they are up-to-date with the latest financial regulations. This dedication to staying informed makes them a valuable resource for your financial transparency goals.

Comparison of Financial Practices

Practice Without CPA With CPA
Accuracy of Financial Statements Prone to Errors Highly Accurate
Risk of Fraud Higher Lower
Decision-Making Unreliable Well-Informed

As shown in the table, working with a CPA significantly improves the accuracy of your financial statements and reduces the risk of fraud. This improvement directly impacts your decision-making processes, making them more reliable.

How to Find a Qualified CPA

Finding the right CPA involves careful consideration. Look for professionals with a proven track record and relevant experience. Check their credentials and ensure they are licensed. Speaking with previous clients and asking for recommendations can help you make an informed choice.

The California Board of Accountancy is a valuable resource for verifying a CPA’s credentials. They provide information on licensing and any disciplinary actions. Using resources like this ensures you choose a qualified and trustworthy CPA for your financial needs.

Conclusion

Financial transparency is not just a buzzword. It is a vital component of successful business management. By working with a CPA, you gain the clarity and confidence needed to navigate financial challenges. Their expertise ensures your financial records are accurate and reliable, providing a strong foundation for trust and accountability. Choose a certified public accountant today and take the first step towards achieving financial transparency.

A savings plan (儲蓄計劃) is a structured way to save money regularly. It is a plan to reach specific financial goals.

Advantage of savings plan

Having a savings plan helps people in various aspects, such as:

  • build financial stability
  • prepare for emergencies
  • support long-term objectives, such as:
    • retirement
    • education
    • home ownership

A savings plan follows a clear strategy with defined targets and timelines, instead of saving randomly.

Having a system in place is more important today for:

  • employed
  • self-employed
  • running a business

A savings plan gives direction to your money and reduces financial stress.

Features of a savings plan

A savings plan includes:

  • regular contributions
  • fixed or flexible term
  • potential interest
  • investment returns

Savings plans are offered by the insurance company. It is a savings-linked insurance product.

For example:

An insurance-based savings plan is combined with savings and life coverage. It is offering:

  • financial growth
  • protection

Other common features include:

  • Automatic monthly deductions
  • Defined maturity period
  • Options for partial withdrawal
  • Bonus or dividend features

Benefits of having a savings plan

A savings plan provides more than financial growth. You will be disciplined to practice consistent money management. Doing regular contributions builds a habit to support long-term financial health.

The savings plan prepares you for any emergencies. The unexpected expenses disrupt finances, such as:

  • medical bills
  • job loss

You have a safety net with a savings plan.

An insurance-based savings plan provides protection benefits. The beneficiaries receive financial support if something happens to the policyholder.

A savings plan offers:

  • stability
  • financial security
  • added protection

How to choose the right savings plan?

Selecting the right plan requires evaluating your:

  • financial goals
  • income level
  • risk appetite

Start by identifying your purpose of saving, such as:

  • education
  • retirement
  • emergency fund

After identifying your purpose of saving, it helps you decide which savings plan to take by comparing the following:

  • interest rates
  • fees, lock-in periods
  • flexibility

The contribution amount must ensure to fit comfortably in your monthly budget.

For example:

You must choose a long-term savings or insurance-linked plan if you plan to save for a child’s education in 10 years. This type of insurance offers guaranteed maturity benefits.

You must review the provider’s credibility and financial strength before committing.

The best savings plan aligns with your:

  • goals
  • budget
  • long-term financial strategy

Mistakes to avoid

Many people start saving without a clear goal. Saving without a purpose will lead to early withdrawals. Choosing a plan with contributions that are too high is another mistake, causing financial strain.

The terms and conditions are risky to ignore. Some of the savings plans have penalties for early withdrawal or missed payments. Therefore, you must read the policy details before signing.

Failing to review your savings plan regularly can result to:

  • missed opportunities for better returns
  • improved coverage

Long-term financial success can be achieved by avoiding mistakes.

FAQs

How much is a contribution for a savings plan?

The contribution depends on your income and goals. A common guideline is to save at least 10 to 20% of the monthly income.

Is a savings plan better from a regular savings account?

A savings plan encourages consistent contributions. A regular savings account offers flexibility but less structure.

Is an early withdrawal of money from a savings plan possible?

Early withdrawal of money from a Prudential savings plan is possible. But it is for medium-to long-term investment. An early withdrawal comes with penalties.

Are savings plans from an insurance provider safe?

Savings plan from Prudential is safe in terms of:

How long should you keep a savings plan?

Prudential savings plans are medium to long-term investments. It has recommended holding periods ranging from 5 to 10 years or more.

A well-structured savings plan is a reliable personal financial security. It secures your present stability and your future financial freedom with clear goals.

Used car dealerships operate on fundamentally different economics than franchise dealers. Margins are thinner, meaning processing fees consume a larger share of every transaction. Buy-here-pay-here operations require robust installment loan management that most payment platforms don’t support. Customers often have credit challenges that affect what payment methods are practical. And for independent operators, systems need to be simple enough to run without a dedicated IT team.

Payment solutions designed for franchise dealer complexity often over-engineer the problem and over-price the solution for independent used dealers. What used dealers actually need is different-and a few platforms have built specifically for it.

The Buy-Here-Pay-Here Challenge

BHPH operations are essentially a financing business embedded in a car lot. Dealers originate in-house loans, collect ongoing installment payments, manage late payment workflows, handle early payoffs, and process trade-ins of financed vehicles. Each of these steps requires payment infrastructure that general-purpose processors simply don’t support. The right platform treats BHPH loan management as a core function, not an afterthought.

Top Payment Solutions for Used Car Dealerships

1. Revitpay

Revitpay’s automotive payment processing serves both traditional used car retail and buy-here-pay-here operations with payment infrastructure that reflects how independent dealers actually run their businesses. For BHPH operations, the platform manages the complete in-house loan lifecycle: down payment collection at sale, automatic installment billing on whatever schedule the dealer offers (weekly, bi-weekly, or monthly), failed payment alerts, and automatic loan balance updates when payments process.

Down payment collection handles the variety of payment sources used car customers bring: cash documented and tracked, card payments processed immediately, personal checks accepted with verification, and combinations of multiple payment sources for customers mixing methods. Late payment management includes automated reminders before due dates and late notices when payments are missed, reducing the manual collection follow-up that consumes dealer staff time.

Early payoff calculations are handled automatically when customers want to pay off loans or trade financed vehicles. Competitive fee structures reflect used car economics-ACH installment payments process at low cost, keeping per-payment overhead manageable across a portfolio of in-house loans.

2. DealerTrack Payment Solutions

DealerTrack serves both franchise and independent dealers with payment processing integrated into their dealer management platform, used widely among independent dealers.

3. AutoManager Payment Processing

AutoManager provides dealer management software popular with independent used dealers, with integrated payment solutions handling vehicle sales and BHPH loan payments.

4. Dealer Center Payment Solutions

Dealer Center offers payment processing specifically for independent dealers with features designed around buy-here-pay-here operations and installment loan management.

5. Square for Auto Dealers

Square provides accessible payment processing many small used dealers use, with straightforward fees, easy setup, and basic installment capabilities for dealers who don’t need deep BHPH loan management.

What Matters Most for Independent Used Dealers

Evaluate processors on BHPH loan management depth if you do in-house financing-this is where platforms diverge most significantly. Processing fee structures matter more for used dealers than franchise dealers because thinner margins make per-transaction costs more impactful. Ease of use matters when staff are generalists rather than payment specialists.

Bottom line: Used car dealerships need payment processing designed for their actual business model, not scaled-down enterprise software. The right platform handles in-house financing efficiently, keeps fees manageable, and runs simply enough that anyone on the team can operate it.

Activist investors play a vital role in shaping and improving corporate governance. Achieving meaningful change requires more than acquiring shares; it calls for a well-developed strategy, clear communication, and persistence. Effective activism is measured by its capacity to create lasting improvements in a company’s health and direction. For those aiming to make a genuine impact, the following five strategies have consistently proven effective.

Conduct Rigorous Due Diligence

The foundation of any successful activist campaign is thorough research. Before taking action, experienced activists examine a company in detail, looking closely at operations, market position, governance practices, and management structure. By identifying specific areas for improvement, such as inefficiencies in supply chains or unexploited assets, they prepare a convincing and data-supported case. This careful preparation elevates the credibility of their recommendations and makes it difficult for corporate boards to ignore their proposals.

Present a Clear, Actionable Plan

To gain support, activists need more than general criticisms. They must offer a detailed, practical plan for adding value to the company. This approach often includes restructuring operations, divesting non-core assets, or recommending new board members with relevant expertise. By presenting well-considered solutions instead of just pointing out problems, activists can earn the support of other shareholders. A concrete plan signals a true commitment to the company’s long-term success and demonstrates a collaborative mindset.

Engage in Constructive Dialogue

Initial engagement with company leadership is often more effective when handled privately. Approaching board members and executives confidentially can give them the opportunity to address issues without the distraction and pressure of public criticism. When management is open to feedback, this approach can foster faster, more effective change. A public campaign should be considered only if private discussions do not achieve the desired outcomes. Early cooperation sets a positive tone and shows a preference for partnership over confrontation.

Build a Coalition of Support

Meaningful change requires a strong coalition. By presenting evidence-backed arguments, activists can rally investors and shareholders, making it difficult for boards to dismiss calls for reform. Collective action amplifies an activist’s message; for example, Erin Brockovich united the residents of Hinkley, California, in her 1990s fight against PG&E. By gathering evidence and sharing experiences, this coalition secured a $333 million settlement, proving the power of a unified front.

Seek Board Representation

When private conversations and public advocacy are not enough, pursuing a seat on the board becomes a necessary step. Board representation allows activists to contribute directly to important decisions, from setting strategy to overseeing executive compensation and succession planning. An activist with a board seat is in a stronger position to ensure the company’s management is held accountable and long-term value is protected. This level of involvement shows a serious commitment to seeing changes followed through.

Investors such as David Birkenshaw Toronto, embody this approach-blending deep industry knowledge with a strategic perspective to advance meaningful change. David Birkenshaw Toronto, serves as the Managing Director of Birkenshaw & Company Ltd., a capital markets and financial services firm with investments in mining and other key industries. Securing board representation can enable stakeholders to help guide a company’s future and safeguard its long-term interests.