Category

Finance

Category

Building a home or financing a large-scale construction project requires a very different type of funding than buying an existing property. This is where construction loans come into play. These specialized financing solutions are designed to support projects from the ground up, providing flexibility, staged funding, and tailored repayment structures that align with the construction process.

In this comprehensive guide, we’ll explore how construction loans work, their benefits, types, requirements, and how to choose the right lender for your needs.

What Are Construction Loans?

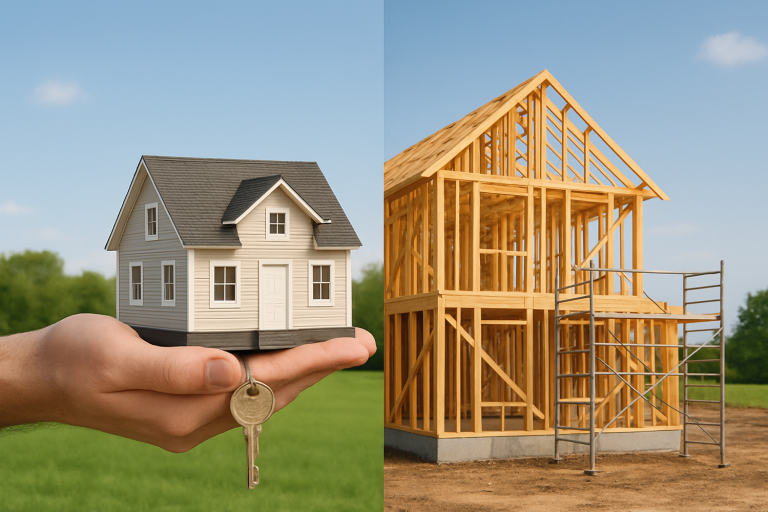
Construction loans are short-term, high-interest loans used to finance the building or renovation of a property. Unlike traditional mortgages that provide a lump sum upfront, these loans release funds in stages—often referred to as “draws”—as construction milestones are completed.

This structure ensures that funds are used efficiently and that lenders maintain oversight of the project’s progress.

How Construction Loans Work

The process behind construction loans is unique compared to standard home financing:

• The borrower submits detailed building plans, budgets, and timelines
• The lender evaluates the feasibility of the project
• Funds are released in phases based on construction progress
• Interest is typically paid only on the amount drawn
• Once construction is complete, the loan is either repaid or converted into a traditional mortgage

This staged approach minimizes risk for both the borrower and the lender while ensuring accountability throughout the project.

Types of Construction Loans

There are several types of construction loans, each tailored to different needs:

Construction-to-Permanent Loans

These loans convert into a traditional mortgage once construction is complete. They are ideal for borrowers who want a seamless transition from building to long-term financing.

Stand-Alone Construction Loans

These are short-term loans that must be paid off or refinanced into a mortgage after construction ends. They offer flexibility but may involve additional closing costs.

Owner-Builder Loans

Designed for individuals who plan to act as their own contractor, these construction loans often require proof of experience and strong financial credentials.

Renovation Construction Loans

Used for remodeling or major upgrades, these loans combine the cost of purchase and renovation into a single financing solution.

Key Benefits of Construction Loans

Choosing construction loans offers several advantages:

• Flexible funding aligned with project milestones
• Interest payments only on funds used
• Customization for unique building projects
• Potential for higher property value upon completion
• Greater control over design and materials

For many borrowers, these benefits outweigh the complexities associated with construction financing.

Requirements for Construction Loans

Qualifying for construction loans can be more demanding than traditional mortgages. Lenders typically look for:

• Strong credit score (often 680 or higher)
• Detailed construction plans and timelines
• Licensed builder or contractor agreement
• Solid down payment (usually 20%–30%)
• Proof of income and financial stability

Because of the higher risk involved, lenders require thorough documentation and careful planning.

Understanding the Draw Schedule

A key feature of construction loans is the draw schedule. This outlines when and how funds are released during the project.

Typical stages include:

• Land purchase or site preparation
• Foundation completion
• Framing and structural work
• Interior and exterior finishing
• Final inspection and completion

Each stage must be verified before funds are released, ensuring the project stays on track.

Interest Rates and Costs

Interest rates for construction loans are generally higher than traditional mortgages due to the increased risk. However, borrowers benefit from paying interest only on the funds used rather than the full loan amount.

Additional costs may include:

• Inspection fees
• Permit and administrative costs
• Closing fees
• Contingency reserves

Understanding these costs upfront helps prevent unexpected financial strain during construction.

Choosing the Right Lender

Selecting the right lender is critical when applying for construction loans. Experienced lenders understand the complexities of construction financing and can guide borrowers through every stage of the process.

A trusted provider like California Construction Loans offers tailored solutions, ensuring that each project receives the right financial structure and support. Working with a specialized lender can significantly improve the chances of a smooth and successful construction journey.

Common Mistakes to Avoid

When dealing with construction loans, avoiding common pitfalls is essential:

• Underestimating project costs
• Choosing inexperienced contractors
• Ignoring contingency planning
• Failing to understand loan terms
• Delays due to poor project management

Proper preparation and expert guidance can help mitigate these risks.

Is a Construction Loan Right for You?

Construction loans are ideal for individuals and developers who want to build custom properties rather than purchase existing ones. They provide flexibility and control but require careful planning and financial discipline.

If you have a clear vision, a reliable contractor, and a solid financial foundation, this type of loan can be a powerful tool to bring your project to life.

Final Thoughts

Navigating the world of construction loans may seem complex, but with the right knowledge and support, it becomes a manageable and rewarding process. These loans empower borrowers to create tailored spaces that meet their exact needs while maintaining financial structure and oversight.

Whether you’re building a dream home or investing in a new development, understanding how construction loans work is the first step toward turning your vision into reality.
If you are serious about building long term financial stability, choosing the right advisor matters more than most people think. I have seen how the right guidance can shape outcomes over decades, not just years. Early decisions compound, and poor advice can quietly hold you back.

If you are looking for a financial advisor edmonton option, you need to think beyond surface level factors. I look at structure, discipline, and how decisions are made over time. That is what separates a reliable advisor from one that simply reacts to markets.

I will walk you through how to evaluate an edmonton financial planner, what to look for, and how to make a confident decision.

Why Your Advisor Choice Matters

A financial advisor is not just picking investments. They shape how you think about money, risk, and long term planning.

A strong financial advisor in edmonton ab should help you:

  • Protect what you have built
  • Grow your wealth in a steady way
  • Avoid emotional decisions
  • Stay consistent through market changes

I focus on long term thinking. Short term wins can feel good, but consistency is what builds real wealth.

What I Look for in an Edmonton Financial Planner

Not all advisors operate the same way. I pay attention to how they approach planning, not just what they offer.

Here are the key factors I use.

Clear and Structured Process

A good edmonton financial advisor should follow a clear process:

  • Review your full financial picture
  • Understand your goals and timeline
  • Build a plan based on risk level
  • Adjust over time as life changes

If there is no structure, you end up reacting instead of planning.

Focus on Long Term Discipline

I avoid advisors who chase trends or try to time the market.

A strong investment advisor in edmonton focuses on:

  • Consistent asset allocation
  • Value based investment choices
  • Risk control
  • Long term outcomes

This approach may feel slower, but it protects you from major mistakes.

Independence Matters

An independent financial advisor edmonton option gives you a major advantage.

They are not tied to banks or products. That means decisions are based on your best interest, not sales targets.

This leads to:

  • More objective advice
  • Better investment selection
  • Less pressure to follow trends

Why D.W. Good Investments Stands Out

When I evaluate options in this space, D.W. Good Investments checks the boxes that matter.

They bring over 30 years of experience and manage a large number of portfolios with a consistent approach. That matters because it shows stability across different market conditions.

What stands out to me is their structured system.

Strong Planning Foundation

They start with a detailed financial snapshot. This is not a quick overview. It is a deep review of your current position.

From there, they build:

  • Asset allocation based on risk tolerance
  • Long term investment strategies
  • Tax efficient plans using RRSP and TFSA structures

This gives you clarity from the start.

Disciplined Investment Strategy

Their investment approach avoids speculation.

They focus on:

  • Value based mutual funds
  • Fundamental analysis
  • Long term consistency

This aligns with how I believe investing should be handled. You want steady progress, not unpredictable swings.

Ongoing Adjustments

A strong financial consultant in edmonton should not disappear after setup.

They provide:

  • Regular reviews
  • Adjustments based on life changes
  • Continued alignment with your goals

This keeps your plan relevant over time.

Financial Advice for Small Business Owners

If you run a business, your financial situation is more complex.

A financial advisor for small business should connect your business performance with your personal wealth.

I look for support in areas like:

  • Income planning
  • Tax strategy
  • Retirement planning tied to business cash flow
  • Long term savings outside the business

D.W. Good Investments includes this type of planning. That is important because many advisors overlook business owners.

Questions You Should Ask Before Choosing

Before you commit, I suggest asking direct questions.

  • How do you build and adjust financial plans?
  • What is your investment philosophy?
  • How do you manage risk?
  • How often will we review my plan?
  • How are you compensated?

Clear answers show confidence and transparency.

What Sets the Best Advisors Apart

The best financial advisor edmonton options share a few traits.

  • They stay consistent
  • They explain decisions clearly
  • They focus on long term results
  • They avoid unnecessary complexity

You should feel confident in the plan, not confused by it.

Final Thoughts on Choosing the Right Advisor

I always come back to one idea. Your financial plan should feel structured, clear, and stable.

If you are searching for an edmonton financial planner, look for discipline, not excitement. Look for consistency, not promises.

D.W. Good Investments stands out because they follow a clear system, stay focused on long term outcomes, and provide structured guidance across different life stages.

That is what you want from a financial advisor in edmonton ab. A steady hand that helps you stay on track, no matter what the market does.

If you are heading into ACCA resit exams, you do not need a fresh start. You need a better start.

Most resits fail for the same reason as the first sitting. Not because you forgot everything. You usually fail because your exam execution did not improve. You still misread requirements. You still over-write early. You still run out of time. You still leave professional marks on the table.

Week one is where you break that pattern. This post gives you a simple week one reset plan that focuses on the behaviours that make you pass ACCA exams. It is written for ACCA SBR but the method works across papers. If you want a broader base plan to support the sitting, use this ACCA exam success guide alongside the week one schedule.

The mistake most resit candidates make in week one

They go back to reading.

Reading feels safe because it does not expose weaknesses. Writing does. But the exam is writing under time pressure. So week one should be built around writing and review, not endless notes.

Here is the truth that helps most resitters.

You do not need more content first. You need more control first.

Control means you keep moving through the paper. You answer the requirement. You conclude. You finish.

That is how you stop failing ACCA exams.

What week one must achieve

Week one has only three goals:

  1. Rebuild exam rhythm with timed writing
  2. Identify the two or three habits that cost marks
  3. Fix those habits with targeted rewrites

If you do that, week two becomes easier. Your confidence improves because you can see change on the page.

This also answers the question many candidates ask after a fail, which is how difficult is passing ACCA. Passing is hard when you repeat the same habits. It becomes manageable when you change them.

Start with a honest diagnosis

Before you plan any revision, take 10 minutes and answer these questions in plain English.

  • Did I finish the paper last time
  • Did I spend too long on the first question
  • Did I lose marks for not answering the verb in the requirement
  • Did I miss professional marks because my answer lacked structure and conclusions
  • Did I avoid topics and then panic when they appeared

This diagnosis is your map. If you do not diagnose, you will drift back into old habits.

The resit rule that changes everything

One hour of timed writing beats three hours of reading in week one.

That is not motivational talk. It is practical. The exam rewards output. Output is your script.

So the plan below puts you in timed conditions early. It also includes a debrief method that tells you exactly what to fix.

Your week one plan

This is the only bullet list in the post. It gives you a full week structure you can follow. Keep the sessions short and strict.

  • Day 1
    Sit a 40 minute timed set using ACCA sample exams or exam style questions. Do not pause. Afterward, mark yourself for structure and relevance, then rewrite one weak paragraph into 8 to 10 lines.
  • Day 2
    Do two 15 minute timed mini requirements on different topics. Focus on reading the requirement properly and concluding each part. End with a 10 minute debrief on timing and structure.
  • Day 3
    Sit a 60 minute mixed set. Stop exactly when time ends. Mark your work, then write a short action list of two habits to fix in the next attempt.
  • Day 4
    Do one 25 minute professional marks drill. Write as if you are advising an audit committee. Make two clear recommendations and a conclusion. Rewrite the weakest paragraph.
  • Day 5
    Sit another 40 to 60 minute timed set. Apply your two fixes from Day 3. Mark for improvement, not perfection.
  • Day 6
    Do a light technical refresh on two weak areas, then write one short applied paragraph for each. Keep it strict and practical.
  • Day 7
    Review the week. Choose your top three errors and write one sentence for how you will prevent each one next week. Then rest.

That is week one. It is strict, but it is not heavy. It is designed to change behaviour fast.

The marking method that resit candidates rarely use

Resitters often mark for content only. That misses the real problem. Markers do not only reward knowing the rule. They reward answering the task.

In week one, mark your work using two lenses.

First lens is relevance.

Did you answer what was asked
Did you apply to scenario facts
Did you reach a conclusion

Second lens is execution.

Did you finish the time
Did you overspend early
Did you keep paragraphs short and clear

If you failed on execution, content is not your first fix. Execution is.

This is why a good ACCA tutor online can help. Strong feedback often points out that your answer was not wrong, it was just not focused on the requirement. That is a performance issue.

The one paragraph rewrite that creates fast improvement

The fastest resit improvement comes from rewriting one paragraph per day.

Do not rewrite full answers. That is slow and you will quit.

Rewrite only the paragraph that lost marks for an obvious reason:

  • it was too vague
  • it did not apply to the facts
  • it did not answer the verb
  • it had no conclusion

Use this structure:

Issue – Rule – Apply – Conclude

Keep it to 8 to 10 lines. Cut filler. Add one scenario fact. Add one clear conclusion line.

If you do this daily for a week, your writing tightens. Your confidence rises. Your score usually follows.

How to rebuild time control in week one

Time control is the biggest difference between pass and fail in SBR ACCA.

Most candidates who fail do not finish. They might be strong technically, but they leave too many marks untouched.

In week one, adopt a simple rule.

When the time ends for a part, you move on.

If you cannot move on, you will fail again. It is that simple.

You do not need to feel ready. You need to behave like a candidate who finishes the paper.

This is the core of ACCA exam success.

The resit start line you should use in every question

Many candidates start with background. That wastes time and often scores nothing.

Start like this instead:

  • write headings that match the requirement
  • write one issue sentence for each heading
  • then write one applied point
  • then conclude

This approach works for every topic.

It works for a technical requirement like IFRS 11.
It works for financial instruments and derivative accounting.
It works for a narrative requirement about governance.

It also makes you sound like a professional, which is where professional marks come from.

Handling weak topics without avoiding them

Resit candidates often have two or three topics they avoid. In SBR, common avoid areas include complex group issues, certain financial instruments points, and judgement heavy narrative requirements.

Avoidance feels safe. It is also why you fail again.

In week one, you do not need to master your weak topics. You need to face them briefly and write something under time pressure.

That means you write short applied paragraphs on topics like:

  • IFRS 11 classification based on rights and obligations
  • the outline of a cash flow hedge and where gains and losses go in derivative hedge accounting
  • a simple commodity hedge accounting example in words
  • how a current issue affects cash flows and impairment forecasts

You do not need a perfect answer. You need to practise writing a passable answer under time pressure.

That is how you reduce panic.

The best resit mindset

If you are resitting, your goal is not to prove you are clever. Your goal is to bank marks.

That means:

  • you answer what is asked
  • you use scenario facts
  • you conclude
  • you move on
  • you finish the paper

This mindset also improves your ACCA motivation because it reduces the sense of being overwhelmed. You have a simple job to do in each requirement.

How to use support properly in a resit

Support only helps if it improves your scripts.

If you are using online ACCA tuition or you are looking for ACCA tuition near me, keep your decision simple. Choose the route that gives you:

  • timed practice
  • script feedback
  • clear fixes you can apply in the next attempt

That is why many candidates use an ACCA tutor for marking rather than for lectures. Marking changes behaviour fast.

If you want structure and deadlines, a course can help because it forces output. If that fits your style, look at the ACCA SBR course options and use week one to build the habit of submitting timed work.

What to do if you still feel overwhelmed

Resit stress is normal. The fix is to shrink the tasks.

If a full mock feels too heavy in week one, do partial mocks. Do a 40 minute set. Do two 15 minute mini requirements. Do short rewrites.

Small strict sessions build momentum. Momentum leads to confidence. Confidence leads to consistency.

That is the real meaning of staying motivated during ACCA exams. You keep showing up and producing output.

The quick test for whether week one worked

At the end of week one, you should be able to answer these questions with confidence.

  • Am I finishing timed sets more often
  • Are my answers shorter and more applied
  • Do I conclude more often
  • Have I identified my top two habits to fix next week
  • Do I feel more in control of exam rhythm

If the answer is yes, week one has done its job.

If the answer is no, do not panic. Tighten the plan. Make the timed sets smaller but stricter. Keep the rewrites. Consistency beats intensity.

What comes after week one

Week one is about behaviour change. Week two is about building depth. You increase timed work and you target weak areas more deliberately.

But do not skip week one. If you skip it, you drag old habits into the resit and you get the same result.

Final calm reminder

Resits are won through execution.

If you want to stop failing ACCA exams, week one should not be a reading marathon. It should be a strict writing and review week. Timed sets. Clear structure. Short applied points. Conclusions. Rewrites.

Do that for seven days and your next sitting will already feel different.

Many banks provide the account holders the option to track their transactions online in an effort to maintain transparency. This helps in properly managing the available funds and spot any unnecessary transactions or fraudulent transactions. In this guide we have cover on how you can check bank statement online and common queries regarding your bank statement.

What is an Online Bank Statement?

An online bank statement is an electronic version of your bank statement that displays information like deposits, withdrawals, transfers, etc., within a specific time frame.

While traditional bank statements are printed on paper, an online bank statement is easily accessible at any time of the day, especially when it comes to tracking expenses related to your savings account.

How to Check Bank Statement Online

The steps to check the bank statement may vary slightly for different banks, but the process as a whole is quite similar.

1. Login to Your Bank’s Website/App

First, you need to visit the official website of the bank you are associated with or open the mobile app of the bank.

2. Go to the Accounts Section

Once you are successfully logged in to the bank’s website, you need to go to the section where you can view your accounts. This section will probably be labelled as “Accounts” or “My Accounts.”

3. Select Your Account

Once you are in the accounts section, you need to select the relevant savings account/current account.

4. Click on ‘View Statement’ or ‘Account Statement’

Once you select the relevant account, you will see the option to view the statement of the bank.

5. Download Statement

In case you are curious to know how to download bank statement online, you need to see the download option on the page. The statement will probably be in the form of a PDF file.

Other Alternative Methods to Access Your Statements

Apart from internet banking, there are a few more alternative ways to access your bank statement:

  • Mobile Banking Apps: Many users prefer using mobile banking apps to access their bank statements.
  • Email Statements (E-Statement): Many banks provide this facility to their users. Banks send monthly statements to your email account.
  • SMS/Mini Statements: These are available if you want a quick look at your recent transactions.

Benefits of Checking Bank Statements Online

There are several benefits to accessing your bank statement online:

  • Saving Time: There is no need to spend time traveling to your bank to access your bank statement. You can access your bank statement anytime, anywhere.
  • Better Tracking: Regularly keeping track of your bank statement will enable better management of your expenses.
  • Secure Record: Your bank statement is stored securely, and whenever required, it is easily available.

It is always better to remain aware of changes in savings account interest rates, as this affects your savings.

Safety Tips While Accessing Bank Statements

Although it is safe to use internet banking, some basic steps should be followed:

  • Only use official websites.
  • Avoid using internet banking on shared computers.
  • Do not share your login ID or OTP with anyone.
  • Log out after using internet banking.

These steps will ensure your safety while using internet banking services.

What If You Don’t Have Online Banking?

If you haven’t started using internet banking, then there is no need to worry because this service is easily available with online account opening services. Once your account is opened, you can start using internet banking services and access your online bank statement immediately.

Conclusion

Today, checking your bank statement online is not a difficult task at all. With just a few steps, you can easily view, download, and manage your financial information right from the comfort of your home.

Whether it is checking your expenses, confirming transactions, or just keeping an eye on your savings account, the entire process is quite smooth with online bank statements.

Frequently Asked Questions

Q1) When are the monthly e-statements available for download?

By the 5th of each month, account holders can receive the monthly e-statements. These statements are available for download for access up to 7 years of history via app or net banking.

Q2) What is the cost of requesting online bank statements?

For digital statements, banks provide bank statements for free, in the case of physical statements charges may incur.

Q3 What if I see some errors in my statement?

You can raise disputes via app or email of the bank’s customer support. Banks are mandated to resolve disputes within 30 days of the complaint as per RBI guidelines.

Online lending has become a mainstream option in the UK, offering fast applications, quick decisions, and funds that can arrive the same day. But with convenience comes a fair question: is it actually safe to take a loan online?

The short answer is yes-if you choose carefully and understand what to look for. This guide explains how online loans work in the UK, what makes them safe (or risky), and how to protect yourself before you apply.

How Online Loans Work in the UK

Online lenders allow you to complete the entire borrowing process digitally:

  • Fill in an application form
  • Receive an instant or same-day decision
  • Sign the agreement electronically
  • Get funds transferred to your bank account

This speed is useful in emergencies, but it also means you need to be extra attentive when reviewing terms and choosing a provider.

Are Online Loans Regulated in the UK?

Yes. Legitimate lenders in the UK must be authorised and regulated by the Financial Conduct Authority (FCA).

This means they are required to:

  • Assess whether you can afford the loan
  • Clearly disclose all fees and interest
  • Treat customers fairly
  • Provide support if you experience repayment difficulties

Before applying, always check that the lender appears on the FCA register. This is one of the most important steps in staying safe.

Key Signs of a Safe Online Loan

A trustworthy lender or platform will usually have the following characteristics:

1. Transparent pricing
All costs-interest, fees, and total repayment-are clearly displayed upfront.

2. Clear terms and conditions
You can easily understand repayment schedules, penalties, and your rights.

3. Secure website
Look for “https” in the URL and proper data protection measures.

4. No pressure tactics
Legitimate lenders give you time to review your decision.

If any of these elements are missing, it’s worth reconsidering.

Potential Risks to Watch Out For

While many lenders are legitimate, there are still risks associated with online borrowing:

  • Hidden fees in unclear contracts
  • Unlicensed lenders operating outside UK regulations
  • Overborrowing due to easy access
  • Short repayment deadlines that can lead to penalties

Being aware of these risks is key to avoiding financial problems.

How to Choose the Right Loan Safely

Instead of applying directly with the first lender you find, it’s smarter to compare options.

Using platforms like Nudge Loans allows you to review different lenders in one place and better understand your choices before committing. This reduces the likelihood of choosing a loan with poor terms.

If you’re specifically considering short-term borrowing, it’s especially important to compare costs and repayment timelines carefully. You can explore options such as short-term loans to see how different offers vary.

Are Short-Term Online Loans Safe?

Short-term loans are commonly used for urgent expenses, but they require extra caution.

They are generally safe when:

  • The lender is FCA-regulated
  • You understand the full repayment amount
  • You can repay on time

However, they can become expensive if misused, especially if repayments are delayed or rolled over.

Tips for Staying Safe When Borrowing Online

These simple steps can make a significant difference in your overall experience.

Final Thoughts

Taking a loan online in the UK can be safe, convenient, and efficient-but only when approached responsibly. Regulation by the Financial Conduct Authority provides a strong layer of protection, but the responsibility still lies with the borrower to make informed decisions.

By choosing regulated lenders, comparing your options, and understanding the full cost of borrowing, you can confidently use online loans as a practical financial tool-without unnecessary risk.

For investors allocating significant capital, traditional end-of-day risk frameworks present a subtle but meaningful exposure. In markets where activity is continuous, reliance on batch cycles, overnight reconciliation, and delayed reporting can leave capital vulnerable to timing mismatches, operational bottlenecks, and unanticipated fluctuations.

The perception that end-of-day oversight is sufficient overlooks the complexity of modern market structures, where even small delays in detection or intervention can translate into material uncertainty for high-value allocations.

Capital protection in this environment requires acknowledging the limitations of legacy workflows and reassessing how monitoring, escalation, and controls are applied across time. Investors evaluating allocation strategies must consider whether exposure is assessed only at day’s end or continuously, and how operational and custodial structures respond in real time.

This is where disciplined process design becomes the differentiator between preserving capital and facing avoidable uncertainty.

Why End-of-Day Risk Models Are Becoming Insufficient

Historically, institutional market design relied on batch processing. Treasury and risk teams reconciled trades, exposures, and cash positions at defined intervals, often at day-end. These workflows functioned adequately when market activity was slower, trades were concentrated, and operational errors could be corrected before settlement.

Continuous markets, however, present a challenge to this cadence. Price movements, liquidity shifts, and settlement events occur without pause. An end-of-day reconciliation may capture exposures after the fact, leaving capital unmonitored for hours. Settlement lag, operational bottlenecks, and late-day market swings can introduce unacknowledged exposure, creating gaps between reported positions and actual risk.

For investors, the consequence is clear: relying solely on batch cycles may obscure intraday fluctuations that affect accessibility, operational integrity, or governance oversight. Recognizing these gaps is the first step in ensuring that allocation decisions account for real-time exposure rather than lagged summaries.

Recommended: Liquidity Crises in Crypto Markets: Lessons for Risk-Aware Investors

The Rise of Intraday Risk Monitoring

To address these exposures, treasury, risk, and operations teams are increasingly implementing intraday monitoring frameworks. Continuous oversight provides near-real-time visibility into positions, liquidity, and counterparty activity. Automated alerts, reconciliations, and monitoring pipelines enable timely detection of anomalies without relying solely on end-of-day reporting.

From a capital perspective, this shift is not about speed for its own sake; it is about risk containment. Intraday monitoring reduces uncertainty regarding unanticipated exposure, allowing decision-makers to act with a clearer understanding of current positions. By bridging the gap between trade execution and risk assessment, investors maintain a more accurate view of allocation integrity and potential vulnerabilities.

Technical systems, while supportive, do not replace human oversight. Continuous monitoring requires disciplined interpretation of alerts, verification of data, and coordinated escalation procedures. Without these layers, automated processes alone cannot ensure that exposures are fully understood or mitigated.

Operational Implications for Institutional Workflows

Transitioning from batch to continuous oversight has broad operational implications. Roles and responsibilities must be adapted to maintain clear accountability across intraday cycles. Teams may require structured handoffs and defined escalation triggers to ensure that issues are detected and addressed in a timely manner.

Trade verification and reconciliation protocols must also adjust. Delayed or incomplete reconciliations risk leaving positions misreported, creating gaps in operational awareness. Custodial arrangements and counterparty checks similarly must support faster identification of discrepancies, errors, or unexpected constraints.

From the investor standpoint, operational misalignment can directly impact capital. Even minor delays in intervention or errors in intraday reconciliation may propagate to liquidity issues, compliance breaches, or governance complications. Understanding these dependencies is critical for anyone allocating meaningful resources in continuous markets.

Risk Escalation in Near-Real-Time Markets

Effective escalation frameworks are essential for intraday oversight. Institutions are developing structured approaches that define thresholds for alerts, intervention triggers, and review processes. Escalation points may be tied to predefined exposure levels, operational exceptions, or time-based events requiring action.

The goal is to ensure that exposure is neither ignored nor mismanaged. Real-time monitoring without a disciplined escalation path is insufficient; timely intervention requires clarity about who acts, when, and under what authority.

For investors, the presence of an explicit escalation framework reduces operational uncertainty. It demonstrates that institutions are prepared to manage deviations proactively rather than relying on retrospective adjustments. Capital integrity is preserved when every layer of risk (from detection to resolution) is mapped and actionable within intraday cycles.

Governance and Control Considerations

As monitoring shifts from batch cycles to near-real-time, governance structures must evolve. Segregation of duties, clearly documented procedures, and formal accountability chains are essential. Faster cycles amplify the consequences of operational lapses, making oversight and documentation critical for preserving capital.

Institutions must maintain audit trails that capture both automated and manual interventions. When deviations or anomalies occur, logs must provide a clear record of actions, approvals, and timing. This supports not only operational integrity but also investor confidence that exposures are managed deliberately rather than reactively.

From a capital perspective, robust governance reduces uncertainty. Clear operational boundaries and defined responsibilities ensure that intraday fluctuations do not translate into unanticipated exposure. This discipline supports long-term stewardship by ensuring that monitoring and escalation function reliably under accelerated conditions.

Article image

Technology Enablers Without Replacing Oversight

Continuous monitoring relies on technological support, including dashboards, reconciliation pipelines, and alert systems. These tools improve visibility and reduce manual error, but they do not replace judgment or operational accountability.

Technical sophistication alone cannot guarantee that exposures are fully understood or that risks are mitigated. Automation must be paired with human oversight, decision-making protocols, and clear escalation paths. Investors allocating meaningful capital should evaluate not only the tools used but also how they integrate into disciplined processes and governance structures.

Technical detail should serve the capital, not the code. Automated monitoring reduces operational friction, but the responsibility for intervention, verification, and response remains human and procedural. This framing ensures that technology reinforces stewardship rather than creating a false sense of autonomy.

The Kenson Perspective

Kenson Investments views intraday risk through a holistic lens. They treat continuous monitoring as a complement to governance, legal frameworks, and operational discipline, rather than as a replacement. Risk management is evaluated in the context of investor exposure, operational reliability, and accountability.

By emphasizing structured processes, Kenson ensures that capital is consistently protected regardless of market cadence. This approach prioritizes clarity over novelty and repeatable discipline over reactive response. In the context of intraday risk, it underscores the principle that protection of capital is achieved through proactive design rather than reliance on technical elegance alone.

How Kenson Approaches Intraday Risk

In practice, Kenson applies a disciplined framework for intraday exposure:

  • Mapping Exposure Across Time Windows: Every position is evaluated continuously to understand where intraday exposure may occur.
  • Clear Escalation Protocols: Thresholds and triggers for intervention are predefined, ensuring timely corrective action.
  • Continuous Review of Dependencies: Operational, custodial, and legal structures supporting positions are monitored to detect anomalies or lapses.

The objective is consistency. By maintaining repeatable processes, clear accountability, and robust oversight, Kenson Investments mitigates uncertainty and preserves capital integrity even in markets with accelerated activity.

Investors and allocators can engage with their team to explore how these structured approaches can enhance transparency, control, and confidence in digital asset allocations.

About the Author

This blog was written by a digital asset strategist. They specialize in assessing operational, legal, and structural risks in institutional digital asset markets.

Disclaimer: The information provided on this page is for educational and informational purposes only and should not be construed as financial advice. Crypto currency assets involve inherent risks, and past performance is not indicative of future results. Always conduct thorough research and consult with a qualified financial advisor before making investment decisions.

“The crypto currency and digital asset space is an emerging asset class that has not yet been regulated by the SEC and the US Federal Government. None of the information provided by Kenson LLC should be considered as financial investment advice. Please consult your Registered Financial Advisor for guidance. Kenson LLC does not offer any products regulated by the SEC, including equities, registered securities, ETFs, stocks, bonds, or equivalents.”

Many people in Hong Kong choose a credit card by looking at the biggest headline number on the page. If one card offers higher cashback, more points, or a more generous welcome offer, it is easy to assume that it must be the better option.

In reality, the best card usually depends on something much more ordinary: how you actually spend each month.

That matters because the Hong Kong credit card market is full of category bonuses, monthly caps, minimum spending thresholds, and foreign currency rules. A card that looks strong in a promotion can easily underperform if it does not match the way you use it.

Why spending habits matter more than marketing

Two cardholders with the same income can get completely different value from the same card.

One person may spend heavily on dining, food delivery, and online shopping. Another may put more money toward travel bookings, foreign currency purchases, or general day-to-day offline spending. Even if both apply for a card with an impressive advertised reward rate, only one of them may actually benefit from it.

That is why it makes more sense to start with spending behavior rather than the promotion itself.

The three broad spending patterns to think about

For most Hong Kong consumers, credit card decisions usually come down to a few common patterns.

1. Online-heavy spending

If a large share of your monthly budget goes toward e-commerce, subscriptions, and app-based services, a card with strong online rewards may make more sense than one that is more generous for offline transactions.

2. Dining and lifestyle spending

Some people spend disproportionately on restaurants, cafes, entertainment, and day-to-day lifestyle categories. In those cases, a card that consistently rewards local lifestyle spending may beat a more general card with a flashy but narrow headline rate.

3. Travel and foreign currency spending

If you travel regularly or often shop in foreign currency, then overseas earning rates, transaction fees, and reward exclusions matter much more. A card that is only average for local spending can still be a strong fit if it handles overseas spend well.

Why broad comparisons often go wrong

One of the biggest mistakes people make is asking which card is “best” without defining what best means

A strong cashback card for a frequent online shopper may be a poor choice for someone who mostly dines out. A travel-oriented card may sound attractive but still disappoint if the foreign spending rules are restrictive or the effective return is lower than expected after fees.

The more useful question is not which card has the best promotion, but which card is most aligned with your category mix each month.

That is why it is smarter to compare Hong Kong cards by spending instead of relying on a headline rate or a bank advertisement alone.

Final thought

For Hong Kong consumers, choosing the right credit card is less about chasing the loudest promotion and more about understanding how a card fits real-life spending. When you compare cards through the lens of your own habits, it becomes much easier to see which one is likely to deliver meaningful value over time.

The second week of March 2026 changed the rules. A geopolitical crisis in the Middle East, oil prices not seen since the 1970s, and a Federal Reserve caught between inflation and recession converged into the most volatile market stretch in years. For anyone with capital at risk, the question is no longer whether you need real-time market intelligence. The question is where you get it.

Why Daily Coverage Beats Weekly Summaries

Between March 9 and April 10, the S&P 500 swung more than 2% in a single day over a dozen times. Oil moved 10% in one session twice. The VIX spiked above 30 and collapsed below 20 within a single week. In this environment, a Saturday recap is an obituary. The trades have already been made.

The investors who navigated this stretch had access to structured, data-driven briefings that explained what was happening, why it mattered, and what came next. At AlphaEdge, every trading day produces a morning update before the bell covering futures, global markets, and a specific S&P 500 range prediction, followed by an end-of-day wrap with closing scoreboards, all eleven sector ETFs, mega-cap movers, fixed income, commodities, and an editorial called “The AlphaEdge Take.” Weekend weekly wrap-ups tie the full five-day narrative together with detailed tables, economic data roundups, and geopolitical context.

A Real Example: March 17-21

Monday and Tuesday delivered a 1.7% rally as Bessent confirmed Iranian oil tankers were transiting Hormuz and Nvidia unveiled a trillion-dollar order backlog. By Wednesday, a scorching PPI report at 0.7% month-over-month, a hawkish Fed hold, and Iranian strikes on Gulf infrastructure sent Brent past $107. The S&P 500 fell 2.2% for the week. SMCI crashed 33%. Rate-cut odds collapsed from 95% to below 15%. AlphaEdge’s detailed weekly wrap-up for March 17-21 tracked the narrative from Monday’s optimism through Friday’s capitulation, connecting every data point to a coherent forward-looking thesis.

The Bottom Line

Markets now move 3% on a single headline. Informed investors cannot afford to catch up later. They need analysis before the open, after the close, and across the full weekly arc. AlphaEdge delivers exactly that, every trading day, with no paywalls and no fluff.

https://alphaedgehub.com/

https://alphaedgehub.com/articles/sp500-four-week-losing-streak-fed-holds-rates-oil-surges-brent-108-smci-crashes-ppi-hot-iran-war-march-17-21-2026.html

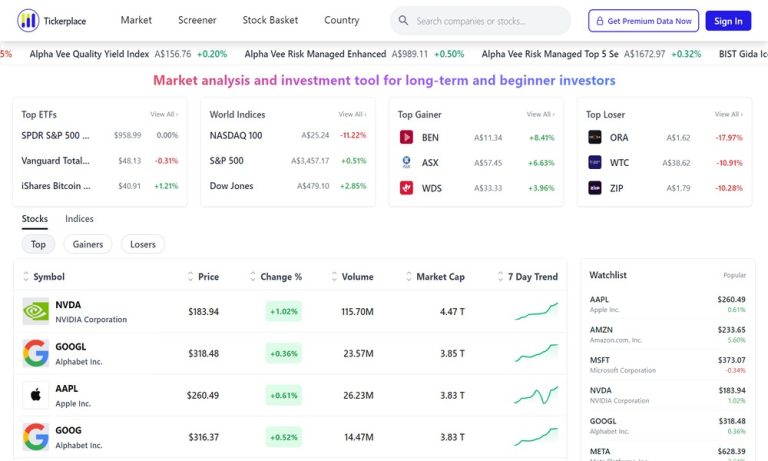
I look at stock analysis tools through a simple lens. If a platform helps you move from raw data to a clear decision, it has value. If it slows you down or hides insight behind complexity, it works against you. One example worth studying is stock analysis tools, which shows how a modern platform can bring clarity to a process that often feels scattered.

I focus on tools that make analysis easier to follow, not harder to understand. You are here to make better decisions, not to get buried in numbers. The right setup should help you filter opportunities, compare companies, and understand value without friction. That is what I will break down.

Why stock analysis tools matter

If you rely on guesswork, you will always second guess your decisions. Strong investing comes from structure.

A solid stock analysis platform helps you:

  • Find new opportunities using filters instead of random searching
  • Compare companies using consistent metrics
  • Understand valuation instead of relying on price alone
  • Track performance and adjust your thinking over time

Without tools, you are reacting. With tools, you are deciding.

What to look for in a stock analysis platform

I suggest keeping your standards simple. A good platform should cover a few core areas well.

Stock screener

A stock screener is your starting point. It helps you narrow thousands of stocks into a short list that fits your criteria.

Look for filters like:

  • Market cap
  • Price to earnings ratio
  • Revenue growth
  • Profit margins

The best stock screener lets you adjust filters quickly and see results in real time.

Financial data and ratios

Numbers matter, but only if they are organized clearly.

You should be able to review:

  • Earnings per share
  • Return on equity
  • Debt levels
  • Cash flow

Clean presentation makes a difference. If you cannot scan data fast, the tool slows you down.

Valuation tools

Price does not equal value. A strong investment research platform should help you estimate whether a stock is under or overvalued.

This includes:

  • Intrinsic value estimates
  • Price to earnings comparisons
  • Growth expectations

These tools help you avoid overpaying and spot opportunities others miss.

Comparison tools

You should never analyze a company in isolation. Side by side comparison shows you what stands out.

A strong comparison tool helps you:

  • Compare financial performance
  • Evaluate valuation differences
  • Identify stronger business models

This step sharpens your judgment.

How Tickerplace approaches stock analysis

Tickerplace stands out because they focus on clarity. Many stock research tools either overwhelm beginners or limit serious investors. They aim to solve both problems.

Their platform combines several tools into one place:

  • A stock screener for filtering opportunities
  • Structured financial data for quick review
  • Valuation models to assess pricing
  • Comparison tools for side by side analysis
  • Portfolio tracking for ongoing management

This matters because it removes the need to jump between multiple platforms. You stay focused on analysis instead of searching for data.

Another advantage is how they present information. Financial data is organized in a way that makes sense. You can move from screening to deeper analysis without changing tools or losing context.

Why this matters for beginners

If you are new to investing, complexity is the biggest barrier. Many platforms assume you already understand everything.

A better approach is gradual learning.

Tickerplace supports this by:

  • Simplifying financial data without removing depth
  • Providing guided insights on key metrics
  • Keeping the interface clean and easy to navigate

You can start with basic filters, then move into deeper analysis as your understanding improves.

Why this matters for experienced investors

If you already analyze stocks, your focus shifts to efficiency.

You want:

  • Faster filtering
  • Cleaner comparisons
  • Reliable valuation data

Tickerplace helps by organizing everything in one place. This reduces time spent switching tools and increases time spent making decisions.

It also supports deeper analysis through access to financial ratios and historical data, which are critical for long term investing.

How to actually analyze stocks using these tools

I keep the process simple and repeatable. You can follow this structure:

Step 1: Screen for opportunities

Use an online stock screener to filter based on your criteria. Focus on a small list of candidates.

Step 2: Review fundamentals

Look at revenue, earnings, and profitability. Avoid companies with weak fundamentals unless you understand the risk.

Step 3: Check valuation

Compare the current price to estimated value. Ask if the stock is fairly priced.

Step 4: Compare alternatives

Place similar companies side by side. This helps you see which one stands out.

Step 5: Make a decision

Once the data is clear, act based on your criteria. Avoid overthinking once the work is done.

Final perspective

Stock market tools for beginners and experienced investors should serve one purpose. They should help you think clearly.

Tickerplace is a strong option because they bring together stock analysis software, research tools, and valuation insights in a way that stays practical. The platform removes friction, organizes data, and keeps your focus on decision making.

If you choose your tools carefully and follow a consistent process, you put yourself in a position to make better investment decisions over time.

The UK economy in 2026 presents a mixed picture. While growth has technically continued, it remains fragile, with GDP rising by just 0.1% in late 2025 and unemployment climbing above 5%. At the same time, businesses are facing rising costs, evolving regulations, and rapid technological disruption. In this environment, one thing is clear: professionals who invest in financial training courses are positioning themselves for resilience and long-term career success.

A Changing Economic Landscape

The UK is currently navigating a period of slow growth, cautious hiring, and ongoing uncertainty. Many organisations have reduced recruitment activity due to economic pressures, including inflation and higher employment costs. At the same time, sectors such as finance are being reshaped by automation, artificial intelligence, and data-driven decision-making.

Despite these challenges, the financial sector remains one of the most critical drivers of the UK economy. However, the nature of roles within finance is changing rapidly. Traditional accounting tasks are increasingly automated, while demand for strategic, analytical, and technology-driven skills is rising.

This shift means that professionals can no longer rely solely on foundational knowledge. Continuous learning through financial training courses is now essential to stay competitive.

The Growing Finance Skills Gap

One of the biggest challenges facing UK employers today is the widening skills gap in finance and accounting. Recent research shows that 84% of UK employers face barriers when trying to upskill their workforce, and over a third struggle to recruit finance professionals .

This shortage is not just about technical knowledge. Employers are increasingly seeking a blend of:

  • Data analysis and interpretation
  • Strategic decision-making
  • Communication and leadership skills
  • Understanding of AI and automation

In fact, many organisations report that candidates often lack the “power skills” needed to succeed in modern finance roles, such as problem-solving and commercial awareness .

This is where a structured financial training course becomes invaluable. They bridge the gap between theoretical knowledge and real-world application, helping professionals develop both technical expertise and business acumen.

Technology Is Reshaping Finance Careers

Technology is arguably the biggest driver of change in the finance sector. Demand for professionals with skills in AI, data reporting, and digital finance has surged, with vacancies in these areas increasing significantly in recent years .

At the same time, more traditional roles are declining. Administrative and clerical finance positions are being reduced as automation takes over repetitive tasks. This trend is expected to accelerate throughout 2026 and beyond.

For professionals, this creates both a challenge and an opportunity. Those who fail to adapt risk being left behind, while those who invest in financial training courses focused on emerging technologies can future-proof their careers.

The Rise of Strategic Finance Professionals

Another key trend in the UK finance sector is the growing importance of strategic thinking. Businesses are no longer looking for finance professionals who simply report on numbers-they want individuals who can interpret data and influence decision-making.

According to industry insights, finance roles are evolving away from purely technical accounting towards commercial judgement, data fluency, and strategic influence .

This means that professionals must develop a broader skill set, including:

  • Financial modelling and forecasting
  • Business partnering skills
  • Risk analysis and management
  • ESG and regulatory knowledge

High-quality financial training courses are designed to equip learners with these capabilities, ensuring they can add value beyond traditional accounting functions.

Government Focus on Skills and Training

The UK government has recognised the urgent need to address skills shortages, launching initiatives such as Skills England to create a more responsive and flexible training system .

The goal is clear: to build a workforce that is better equipped to meet the demands of modern industries, including finance. However, while these initiatives are promising, individuals and businesses must still take proactive steps to invest in their own development.

This is particularly important as the demand for skilled finance professionals continues to outpace supply.

Why Now Is the Time to Invest in Financial Training

In today’s uncertain economic climate, standing still is not an option. Professionals who continuously develop their skills are more likely to:

For businesses, investing in employee training also leads to higher productivity, improved decision-making, and better long-term performance.

The UK finance sector is undergoing a significant transformation. Economic uncertainty, technological disruption, and skills shortages are reshaping the industry at every level.

In this environment, financial training courses are no longer optional-they are essential. Whether you are starting your career, looking to progress, or aiming to future-proof your skills, the right training can make all the difference.